Physical Intelligence's US$20 Billion Price Tag Has No Outside Bidder
Physical Intelligence is reportedly in talks to raise over US$1 billion at a US$20 billion valuation, nearly double its price from earlier this year, with existing investors Avenir and Lux Capital leading the round rather than a new outside backer. The company still has no revenue, and its October API beta names no paying customer.

Physical Intelligence is reportedly in talks to raise more than US$1 billion at a valuation near US$20 billion, almost double the roughly US$11.5 billion figure it carried earlier this year. The company still has no revenue. The investors said to be leading the new round, Avenir and Lux Capital, already own a slice of it.
That last detail is the story. A funding round is supposed to be the moment an outside party, someone with no existing stake and no reason to be generous, looks at a company and decides what it is worth. When the people setting the price already hold the asset, the number stops being a market signal and starts being an accounting exercise.
The Valuation Ladder, Rung by Rung
Physical Intelligence's price history reads like a company doubling its own homework every few months. A US$70 million seed in 2024 valued it at roughly US$400 million. By that November, backers including Jeff Bezos, OpenAI, Thrive Capital and Lux Capital put in US$400 million at a valuation reported between US$2 billion and US$2.8 billion. A year later, in November 2025, Alphabet's CapitalG led a US$600 million round at US$5.6 billion, with Bezos back for a third time. Earlier this year the company raised again at a valuation of roughly US$11.5 billion. The figure now on the table is close to US$20 billion, reached in under a year.
Line those up and the valuation has grown faster than any product the company has shipped.
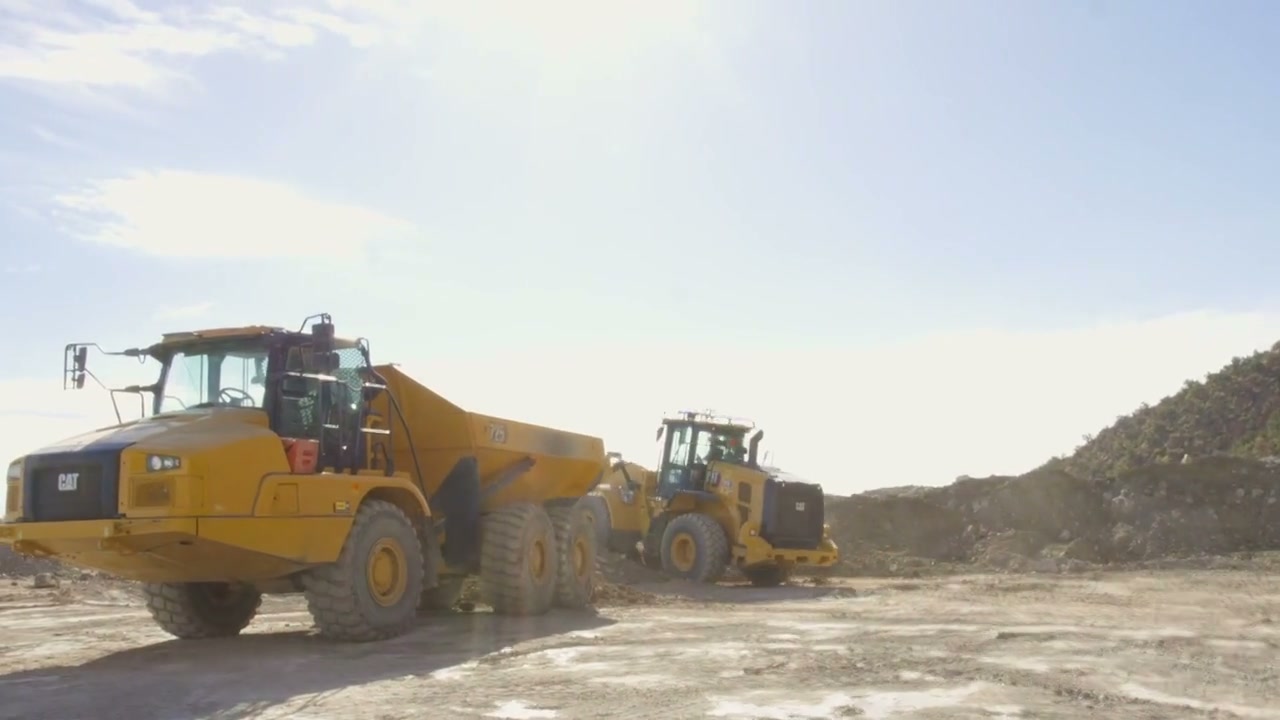
Founded in March 2024 by alumni of Google DeepMind, Physical Intelligence spent most of its life as a research bet with a strong pedigree and no commercial surface at all. Its first real product gesture only arrived on October 13, 2026, when it opened an API beta: developers can upload their own robot demonstrations, run fine-tuning on the company's infrastructure, and call the resulting model through hosted inference. Showcased uses included heavy machinery and a dual-arm robot deburring parts for the company's own assembly line. No named customer appears anywhere in that announcement, two weeks before the latest valuation talk surfaced.
Who Is Actually Setting This Price
Compare the mechanism to Figure AI, the humanoid robot maker that hit a US$39 billion valuation in September 2025. That round was led by Parkway Venture Capital, a new entrant to Figure's cap table pricing a business most of whose prior backing came from a different investor group entirely, up from a US$2.6 billion valuation the year before. Whatever one thinks of a nine-month, fifteen-fold jump, an outside firm did the pricing. It put new money in at a number it had never previously agreed to.
Physical Intelligence's reported round runs the other way. Avenir and Lux are not new names showing up to test the company's worth against the rest of the market; they are existing shareholders proposing to mark up their own position. That is not fraud and it is not even unusual in a hot sector, insiders lead markup rounds across venture capital all the time, often because no credible outsider will set the price the insiders want. But it is a materially weaker signal than the headline number implies, and most of this week's coverage has repeated the US$20 billion figure without pausing on who is actually proposing it.
A round with no new lead investor is a company and its existing owners agreeing on a story. A round with a new lead investor is a company convincing someone who did not already need the story to be true.
The Argument Underneath the Number
Physical Intelligence's public case for why it deserves any of this rests on a specific technical claim, made repeatedly by co-founder Sergey Levine: the constraint on general-purpose robot models is not architecture, it is data, and a model trained across many robot bodies and tasks generalizes better than one trained deep on a single humanoid's repetitions. It is a reasonable research position, and it is also the exact argument every well-funded robot foundation-model company makes to justify raising more money before it has paying customers: we need scale to prove the thesis, and the thesis is why we deserve the scale.
The API beta is the first real test of that argument outside the company's own walls, and the early signal is mixed rather than damning. Physical Intelligence itself has acknowledged connectivity problems with the cloud-hosted inference that most beta applications depend on, a mundane infrastructure issue rather than a model failure, but exactly the kind of friction that separates a demo from a dependable service. Nobody outside the company has yet reported running a paid, production workload on top of it.
None of this means the underlying research is weak. Physical Intelligence's talent and its results on narrow manipulation benchmarks are real, and "data, not architecture" is a defensible bet on where general robot intelligence actually comes from. The weakness is specific: the valuation is running years ahead of the commercial evidence, and the round reportedly financing that gap is being priced by the people least incentivized to find a lower number.
What a Manila Vantage Adds to This
I track funding valuations from the Philippines the way a buyer tracks a supplier's credit rating: not because the number itself tells me what the robot can do, but because it tells me how much runway a company has to keep promising before it has to show results. A US$20 billion valuation buys years of patience from existing investors who are, by definition, already committed to the story being true. It buys nothing from a factory manager in Laguna deciding whether to trust a hosted inference API with a production line, and it should not.
Southeast Asian manufacturers evaluating robot foundation-model vendors over the next two years will be shopping in a market where the loudest valuations and the thinnest customer lists sometimes belong to the same company. That is not an argument against Physical Intelligence specifically. It is an argument for reading "US$20 billion" as a number about investor sentiment, not a number about whether the robot works.
What Would Actually Move the Needle
Three things would change my read on this round, and none of them is the valuation closing at the reported number. A new outside lead investor, one with no prior stake to protect, agreeing to the US$20 billion figure would matter more than Avenir and Lux marking up their own book. A named paying customer running a production workload through the API beta, not a pilot, not a demo, would matter more than another funding headline. And a disclosed success rate on tasks the company did not design its own showcase around would matter more than any number with a "B" after it.
Until one of those shows up, the honest description of Physical Intelligence's position is not "a US$20 billion robotics company." It is a well-credentialed research team whose own investors have agreed, among themselves, that the team is worth that much. Those are different claims, and the gap between them is exactly where the next twelve months of this story will actually be decided.
This analysis is based on public reporting and company statements as of October 29, 2026, and is provided for general information purposes only; it does not constitute investment, financial, or engineering advice. Hero image courtesy of Physical Intelligence, showing an autonomous wheel loader from its API beta showcase.