UBTECH's Humanoid Robots Grew Revenue 1,445%. Its Gearbox Supplier Made the Profit.
China's Q3 2026 robotics earnings reveal a split: component suppliers like Leaderdrive and Hengong Precision post triple-digit profit growth off humanoid robot demand, while assembler UBTECH still posts a loss despite 1,445% segment revenue growth.

Every week this autumn has produced another humanoid robot video: a machine folding laundry, climbing a staircase, walking a factory floor under a banner promising the next generation of embodied intelligence. China's robotics industry just closed its third-quarter reporting season, and the filings nobody filmed tell a sharper story than any of those clips. The companies turning the biggest, cleanest profits are not the ones building the robots. They are the ones building the gearboxes inside them.
In this earnings season, the humanoid robot supply chain is already making money. The humanoid robot brands, almost without exception, are still losing it.
The Suppliers Nobody Photographs
Leaderdrive, the Shanghai-listed maker of the harmonic-drive reducers that let a robot arm or leg bend with precision, booked revenue of RMB591 million (roughly US$82 million) for the first nine months of 2026, up 45.3 percent year over year. Net profit rose 30.3 percent to RMB122 million (about US$17 million). The company has credited the jump to two things at once: a bigger share of the existing industrial-robot-arm market, and a sharp expansion in orders tied to embodied-intelligence, meaning humanoid, programs. That second line did not exist at meaningful scale two years ago.
Hengong Precision, a maker of continuous-cast iron components better known for automotive and machine-tool parts, shows the shift even more starkly. Its robot-components business brought in RMB173 million (about US$24 million) across the first three quarters of 2026, a year-over-year jump of 1,174 percent, lifting that segment to 15.2 percent of total revenue. Nearly RMB100 million (US$14 million) of that arrived in the third quarter alone, more than the business had booked in the first six months combined. A company that spent decades casting parts for car engines is now a robotics supplier because robotics companies started placing orders large enough to notice.
Neither Leaderdrive nor Hengong Precision makes a robot a buyer would recognize by name. That is the point.
The Company Everyone Is Watching
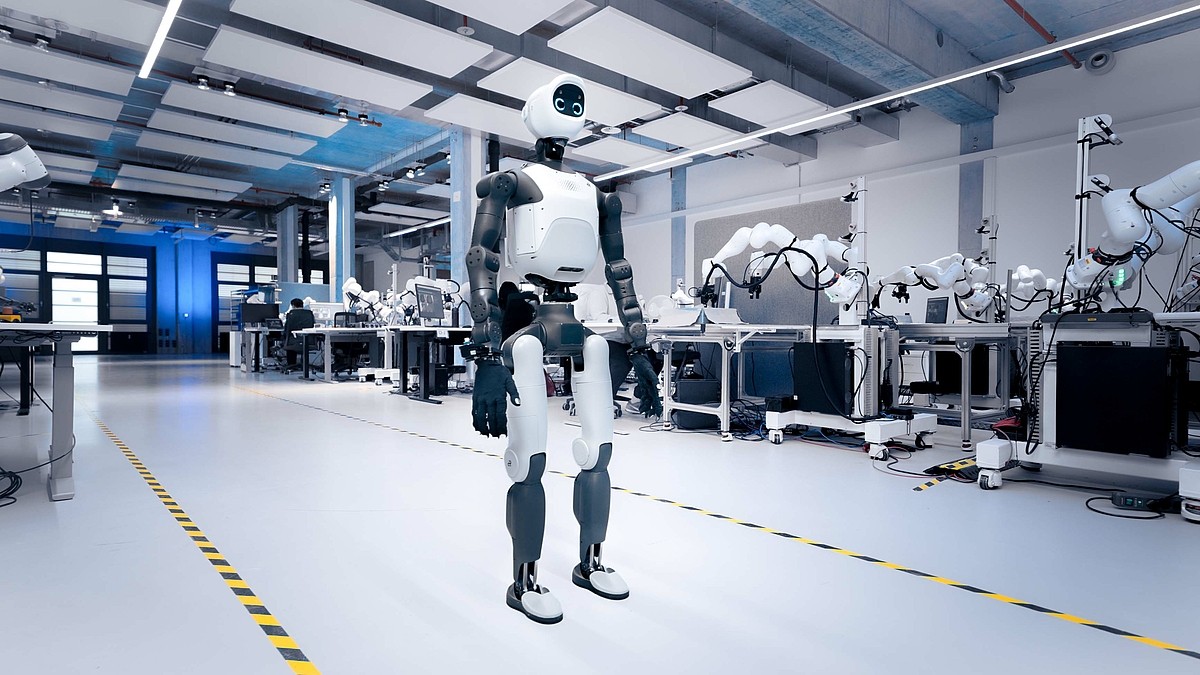
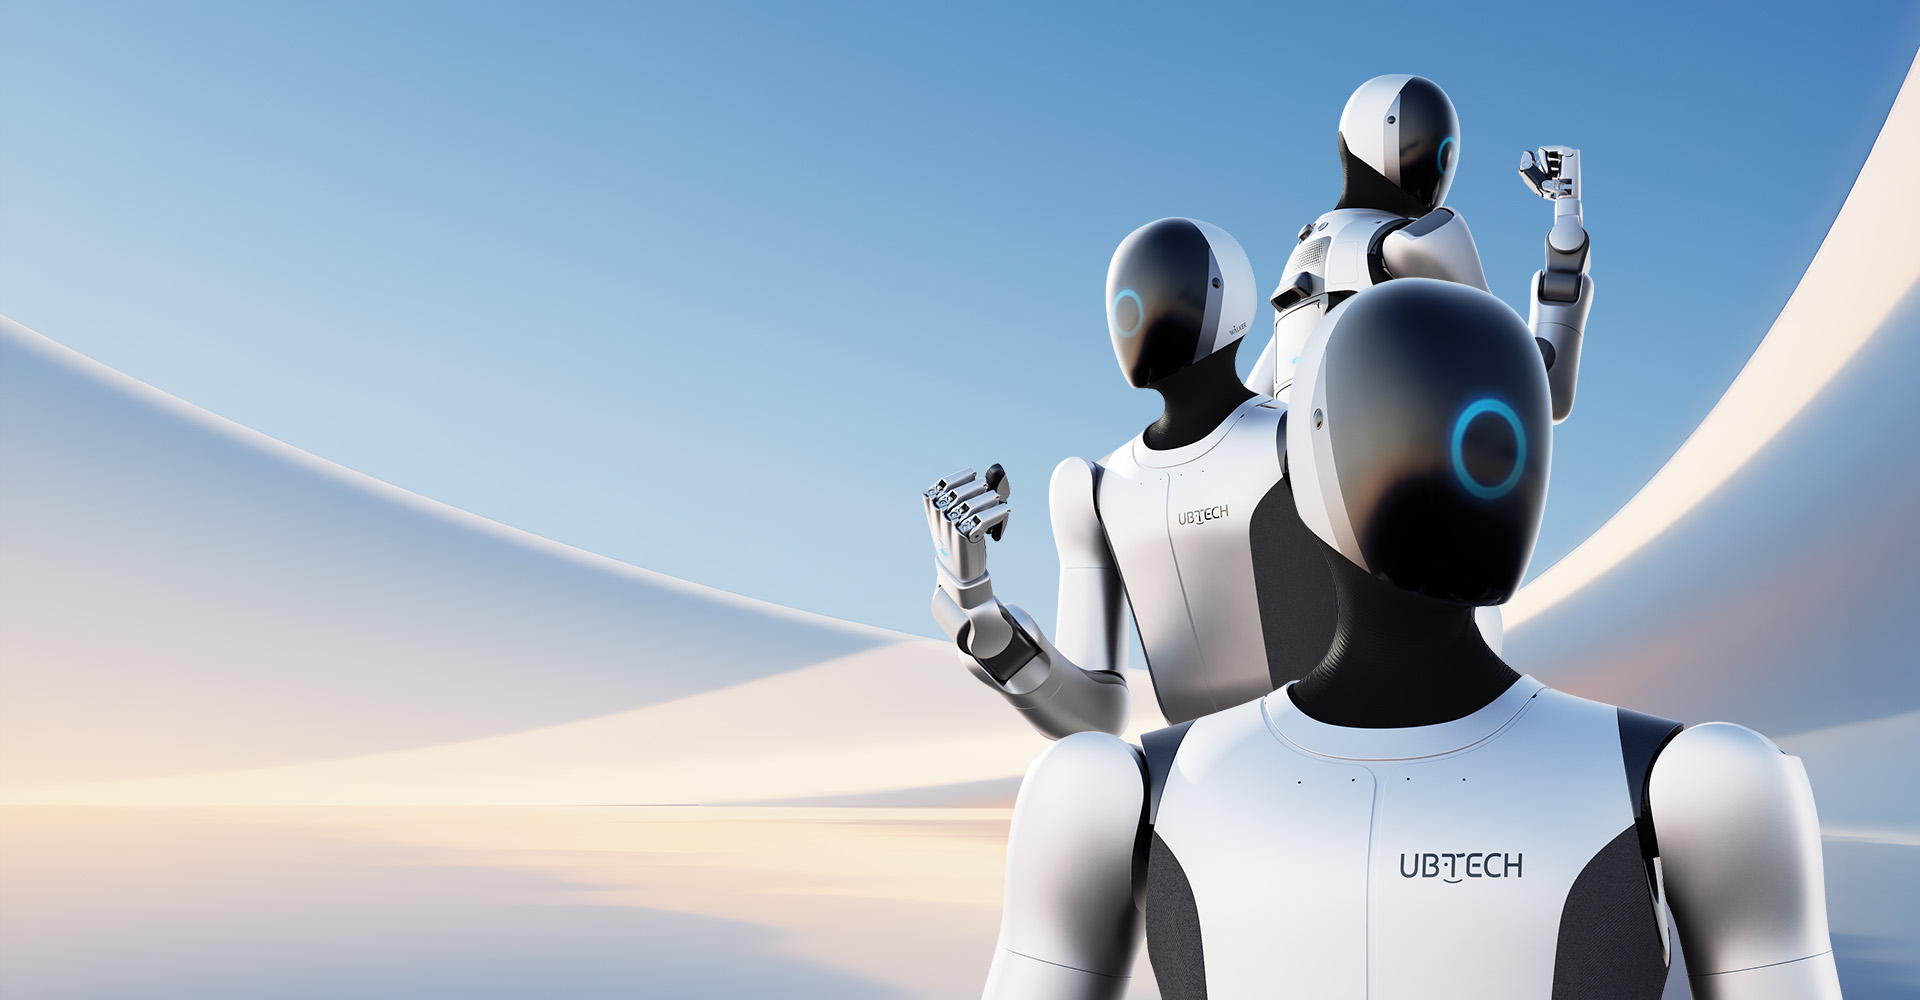
UBTECH, the Hong Kong-listed humanoid maker whose Walker series shows up at trade fairs across China, posted first-half 2026 revenue of RMB1.269 billion (roughly US$176 million), up 104 percent year over year. Full-size humanoid robots and related services accounted for RMB590 million (about US$82 million) of that, a 1,445 percent jump, on sales of 921 units. Gross margin on the humanoid line came in at 66.8 percent, a healthy number by any industrial standard.
UBTECH still lost RMB339 million (roughly US$47 million) in the first half. That loss narrowed from RMB440 million (about US$61 million) a year earlier, and the company is right to call that progress. It is also still a loss, on a company selling fewer than a thousand humanoids against a stated 2026 production target of 10,000 units, meaning the scale that would let gross margin translate into an operating profit has not arrived yet. Revenue up 104 percent and a shrinking loss are both true. Profitable is not one of the words that applies.
Line up the two sets of filings and the gap is specific, not impressionistic: the companies selling 66.8-percent-margin components into the humanoid boom are reporting real, GAAP, no-asterisk profit growth. The company assembling those components into a product with a recognizable face is still burning cash to do it.
The Caveat Inside the Good News
Even the component side of this ledger deserves a harder look before anyone treats it as proof of a clean picks-and-shovels trade. Estun Automation, a servo and motion-control supplier that also sells into humanoid programs, reported nine-month net profit up 1,984 percent to RMB171 million (about US$24 million) on revenue of RMB3.699 billion (roughly US$514 million), which is down 3 percent. More than half of that profit jump, RMB99.5 million (about US$14 million) by the company's own accounting, came from a one-time fair-value gain tied to an affiliate's corporate restructuring, not from selling more servo motors. Strip that gain out and Estun's operating story looks like modest recovery, not the leap the headline number suggests. A sector-wide earnings season this good at masking the ordinary inside the extraordinary is a sector worth reading past the first line of every filing, including the ones that flatter the thesis of this column.
What the National Numbers Say
China's industrial robot output rose 29.1 percent year over year across the first three quarters of 2026, according to the country's statistics bureau. That is a broad, economy-wide number, and it covers arms and carts that have nothing to do with humanoids. The more pointed figure sits inside the Ministry of Industry and Information Technology's own account of the year: domestic humanoid robot production topped 40,000 units in the first half of 2026, with officials projecting full-year output above 100,000 units. Humanoids, in other words, are a real and growing slice of a much bigger, already-functioning robot manufacturing base, not a parallel industry inventing its own supply chain from nothing.
That matters more than it sounds. A components sector growing off a 29-percent-a-year industrial base has existing customers, existing factories, and existing cash flow to absorb a slow humanoid ramp without going under. A humanoid assembler growing off nothing has none of that cushion, which is exactly why the loss column stays red for longer even as the sales column climbs faster.
Where the Capital Actually Sits
Running a platform that tracks company filings and taxonomy data for a living means watching the gap between an investor pitch and a balance sheet longer than most people have patience for, and the gap in this sector right now is unusually clean. Capital chasing the humanoid brand is betting on a production curve that has not bent yet. Capital that found its way into harmonic drives, servo components, and precision casting is already being repaid, quarter after quarter, by customers who have not shipped a profitable robot themselves.
None of this means the humanoid makers are wrong to keep spending. It means the people calling this a gold rush have been pointing at the wrong prospectors. The companies with working profit margins this quarter are not the ones a consumer would ever be asked to buy from directly. They are the ones whose names show up in a bill of materials, not a product launch.
Watch the next two reporting seasons, not this one, for the real signal. If UBTECH's loss keeps narrowing toward its 10,000-unit target and the component makers keep compounding off a bigger base, the picks-and-shovels read holds and probably gets stronger. If a humanoid assembler posts its first operating profit before the component suppliers' growth rate decelerates, the balance of power in this supply chain will have genuinely shifted, and that, not another walking-robot video, is the number worth watching for.
This column reflects the author's own analysis of third-quarter 2026 regulatory filings and public disclosures from UBTECH Robotics, Leaderdrive, Hengong Precision, and Estun Automation, together with published data from China's Ministry of Industry and Information Technology and national statistics agency, and is provided for general information purposes only; it does not constitute investment, financial, or professional advice. Hero image courtesy of UBTECH Robotics, from the company's official Walker S2 product gallery.