Mobile Robotics Funding Concentrated in Fewer, Bigger Bets in 2026
A new CMRA industry report finds that 20 mega-rounds captured 93% of the roughly US$1.19 billion raised by mobile robotics companies through Q3 2026, with Hong Kong IPOs supplying 40% of all disclosed funding.

Mobile robotics financing has not collapsed in 2026, but it has concentrated sharply. A new industry report published October 15, 2026 by CMRA, a Shenzhen-linked mobile robotics research network compiling data with the CMR Industry Alliance and the New Strategy Mobile Robot Research Institute, counts 48 disclosed financing rounds across the AGV, AMR and low-speed autonomous vehicle sector through the first three quarters of 2026, totaling roughly RMB8.49 billion, approximately US$1.19 billion at current exchange rates. The headline number looks modest next to the sector's funding peaks of the past two years, but the distribution behind it tells a sharper story: capital has stopped spreading across the field and started pooling in a small number of large, already-de-risked bets.
Twenty of those 48 rounds, 41.7% of total deal count, qualify as mega-rounds of RMB100 million (roughly US$14 million) or more, and together they account for approximately 93.2% of all disclosed funding. In practical terms, fewer than half the companies that raised money this year captured nearly all of the capital, while the remaining 28 smaller rounds split what was left. That is not a market running out of interest in mobile robotics; it is a market where investors have decided which companies have already cleared the commercial and technical risk bar, and are writing larger checks to fewer of them rather than spreading smaller bets across a wider field.
Buyers reading the data as a vendor-selection signal should separate two things the headline number blurs together: a cooling in the pace of new entrants attracting fresh capital, and the underlying industry's revenue and deployment base, which the report's authors argue is not shrinking at all. The screening effect described below is the more useful lens for procurement teams, because it identifies which vendors still have the balance sheet to support multi-year contracts, not whether the sector as a whole is contracting.
Where the Money Actually Went
Geographically, the capital stayed overwhelmingly domestic. China accounted for 38 of the 48 rounds and about RMB6.79 billion (approximately US$950 million), roughly 79% of both deal count and disclosed funding. The remaining 10 rounds, worth about RMB1.75 billion (approximately US$245 million), were split across the United States, India, South Korea, the United Kingdom, Germany and Singapore, meaning the entire non-China mobile robotics funding market this year amounts to less than a quarter of what Chinese companies alone raised. For buyers and competitors outside China, that imbalance is worth sitting with: the country producing the largest single pool of mobile robotics capital is also the country fielding the largest number of companies competing for industrial, warehouse and delivery robotics contracts globally.
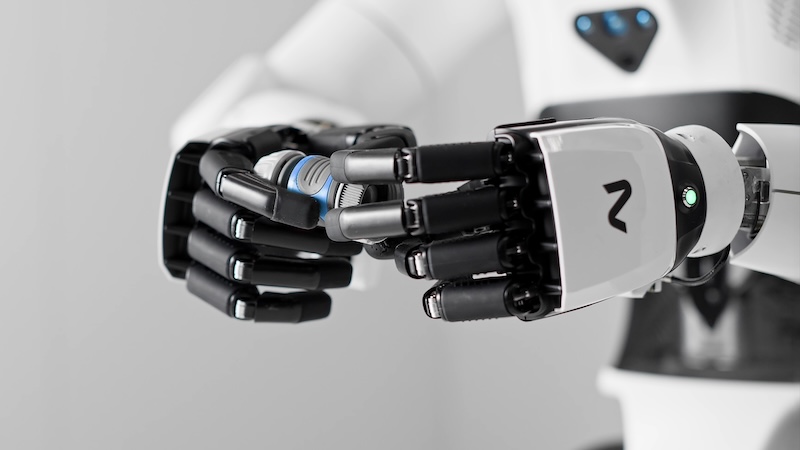
The clearest American data point in the report is Mytra, a Fremont, California-based warehouse robotics company founded by engineers with backgrounds at Tesla and SpaceX, whose cube-based automated storage and retrieval system raised roughly RMB835 million, about US$117 million, making it one of the largest single rounds the report tracks outside China. Locus Robotics, the Wilmington, Massachusetts-based autonomous mobile robot maker long established in warehouse fulfillment, closed a Series G of about RMB280 million, roughly US$39 million, a smaller but still meaningful raise for a company already operating at commercial scale across thousands of warehouse deployments.
The Hong Kong IPO Window Did Heavy Lifting
Public markets, not venture rounds, supplied a disproportionate share of the capital counted in this report. Five Hong Kong IPOs, Kelex, Lody Robot, Yizhidian, Standard Robots and Youdi Robot, together raised about RMB3.43 billion (approximately US$480 million), roughly 40.1% of all disclosed Q1-Q3 funding in the entire dataset. That means a single listing venue, Hong Kong's exchange, supplied nearly as much capital to the mobile robotics sector this year as every private venture round combined. For companies still weighing whether to chase a later and larger private round or pursue a Hong Kong listing sooner, the data this year argues clearly for the public-market path: it has been the single largest funding channel available to the sector in 2026, not a fallback option for companies that could not raise privately.
That pattern extends a trend CMRA's own site has tracked across 2026, in which Chinese robotics companies have increasingly treated a Hong Kong listing as a primary growth-financing tool rather than an exit event for existing investors. Unitree Robotics' own Shanghai STAR Market listing earlier this year drew comparable attention for similar reasons: public markets have become willing to price mobile and humanoid robotics companies at valuations private investors have grown more selective about matching.
A Consumer Robotics Company Crosses Into Mobile Robotics
One of the quarter's larger single rounds came from a company better known for a completely different product category. Dreame Technology, the Suzhou, China-based maker of robot vacuum cleaners and other home-cleaning robots, raised a roughly RMB1 billion, about US$140 million, Series A+ round under its Dreame Innovation unit, backed exclusively by Meituan Longzhu, the robotics-focused investment arm of delivery platform Meituan. The round is notable less for its size than for what it signals about where consumer robotics companies see their next growth market: Dreame built its brand and manufacturing scale selling cleaning robots directly to households, and a single-investor round of this size dedicated to a separate "Innovation" unit suggests the company and its backer see a path from consumer floor-cleaning robots into the broader commercial mobile robotics categories CMRA's report tracks, such as warehouse and facility automation, rather than staying confined to the home-appliance aisle.
Two smaller but named rounds round out the report's picture of where early-stage capital is still willing to go. Jiating Robot closed a round led by investment firm Andrt, and Star Brilliant drew strategic backing from Jiecang, a linear-actuator and motion-component manufacturer, and fellow investor Yate. Both rounds are far smaller than the mega-round tier dominating this year's totals, and the report does not disclose enough detail about either company's product line or stage to support claims about their specific technology or market position beyond the financing itself; they illustrate that smaller, more specialized mobile robotics bets are still getting funded, just in far smaller amounts and in far smaller numbers than the handful of mega-rounds absorbing most of the sector's capital.
South Korea, India, Germany and the Rest of the Overseas Ten
The report names the United States, India, South Korea, the United Kingdom, Germany and Singapore as the six markets splitting the roughly RMB1.75 billion (approximately US$245 million) raised outside China, but discloses deal-level detail for only two of those ten rounds, Mytra and Locus Robotics, both American. That leaves eight rounds across four additional countries whose individual size, investors and company names the report does not break out, which is itself a useful data point for buyers in those markets: South Korea, India, Germany and Singapore's mobile robotics funding activity this year was active enough to register in a China-centric industry tracker, but not yet large or singular enough for any one deal to warrant being named individually the way Mytra's and Locus's were. For a market-intelligence reader outside China, that asymmetry in disclosure is a reminder that China-based trackers see the domestic market with far more granularity than they see fragmented smaller deals spread across several overseas markets, not necessarily that those other markets lack meaningful activity.
What "Quality-Driven Screening" Actually Means for Buyers
CMRA's own framing of the data describes the sector moving into what it calls a quality-driven screening phase, arguing that the tightening of capital does not signify a shrinking industry value. The deal data supports a narrower version of that claim: total disclosed funding and deal count both remain well below the sector's funding peak years, but the concentration ratio, 93.2% of funding going to fewer than half the rounds, shows investors are not withdrawing from mobile robotics broadly. They are instead refusing to fund unproven early-stage bets at the rate they once did, while continuing to write large checks to companies that have already demonstrated commercial traction, whether through deployed fleets, like Locus Robotics, manufacturing scale, like Dreame, or a credible path to public-market exit, like the five companies that chose Hong Kong listings this year.
For procurement teams and automation buyers evaluating mobile robotics vendors on financial stability as a selection criterion, that concentration is useful signal, not noise. A vendor that raised a mega-round or completed a Hong Kong listing in 2026 has cleared a higher investor bar than one that raised a smaller, earlier-stage round in the same period, and that distinction now carries more weight than it did when capital was spread more evenly across the field. The sector's total funding pool may be smaller this year than in its peak years, but the rounds that did close were, on average, bets on companies further along the path from demonstration to deployment, which is precisely the stage buyers should be most interested in when choosing a vendor to commit multi-year capital to.
Ninety-three percent of this year's disclosed mobile robotics funding went to fewer than half of the companies that raised money, a concentration ratio that will determine which vendors have the balance sheet to still be shipping and supporting fleets three years from now.
This account synthesizes CMRA's October 15, 2026 "2026 Global Mobile Robotics Funding Report," crediting the CMR Industry Alliance and New Strategy Mobile Robot Research Institute as data sources, as of the stated publication date. The report's internally inconsistent quarterly breakdown figures were excluded from this account; only its reconciled topline, mega-round, geography and Hong Kong IPO figures are used. No commercial plagiarism-screening database was used; this is an internal source-similarity review against the accessible source corpus.
This article is provided for general information purposes only and does not constitute investment, procurement, legal, or financial advice. Figures reflect the sources listed above as of the stated information cut-off and may change without notice.