China's 'New Quality Productive Forces' Policy Subsidizes Robot Adoption
China's October 9 "New Quality Productive Forces" policy splits robotics into near-term and future-industry tracks, subsidizing both manufacturer R&D and buyer adoption while the NDRC warns against the same overbuilding that hit solar, battery, and EV sectors.


On October 9, 2026, the Communist Party of China (CPC) Central Committee and the State Council in Beijing jointly issued the Opinions on Developing New Quality Productive Forces, a national industrial-policy document that names robotics, humanoid robots and embodied intelligence as priority technologies for the country's next growth phase. The National Development and Reform Commission (NDRC) held a same-day briefing through its High-Technology Department to walk through the logic behind the document, and together the two texts give the clearest picture yet of how Beijing intends to move automation from a research priority into a subsidized commercial reality.
For a procurement team watching China's robotics supply chain, the document matters less for its slogans than for its mechanics. It splits robotics into three separate policy tracks, each moving at a different speed and carrying a different set of financial incentives, and it pairs that structure with an unusually blunt warning from the NDRC about the overbuilding that has already distorted China's solar, battery and electric-vehicle sectors. Both halves change the near-term calculus for anyone sourcing automation hardware, components or integration services out of China.
A Policy With Two Different Clocks for Robots
The Opinions document does not treat robots as a single category. Section seven, on strategic emerging industries, lists robotics alongside next-generation information technology, new energy, new materials, intelligent connected new energy vehicles (NEVs), biomedicine, high-end equipment and aerospace, industries the document instructs regional authorities to accelerate now. Section eight, on future industries, places a separate and more specific term, embodied intelligence, in a different basket alongside quantum technology, biomanufacturing, hydrogen and fusion energy, brain-computer interfaces and sixth-generation (6G) mobile networks, industries the document says should be incubated through a dedicated investment-growth-and-risk-sharing mechanism rather than pushed straight into volume production.
That distinction is the single most useful fact in the document for a buyer trying to time a sourcing decision. Conventional robot hardware, arms, actuators, automated guided vehicles and sensors bundled into fixed automation lines, is treated as mature enough to scale under the near-term demand-side subsidies described below. The harder problem, the general-purpose artificial intelligence (AI) stack that lets a robot handle unstructured tasks without being reprogrammed for each one, is explicitly bucketed as a future industry still being patiently capitalized rather than mandated into deployment. Yet the same document's section ten, on the "AI plus" action, names humanoid robots directly as a next-generation smart-terminal scenario to be scaled commercially alongside AI-enabled phones, computers and intelligent connected NEVs. Beijing is, in effect, pushing the hardware form factor into real-world scenarios on the same track as consumer electronics while the underlying intelligence is still priced as a long-horizon bet, which is exactly the gap between demo performance and deployment reality that has made humanoid-robot economics so hard to model anywhere in the world.
The Subsidy Math That Shortens the Payback Period
The document's concrete financial levers sit mostly in sections two, four and six, and they hit both sides of the adoption equation at once. On the supply side, it instructs authorities to establish a corporate research and development (R&D) reserve system and raise the super-deduction ratio applied to enterprise R&D expenses, which lowers the after-tax cost of the engineering work that goes into a new robot platform. On the demand side, it directs implementation of the first-unit, first-batch application policy, a long-standing Chinese mechanism that shares the cost and insures the risk when a domestic buyer agrees to be the first customer for a newly developed piece of major equipment, a mechanism that explicitly covers automation and robotics hardware, alongside separate tax incentives tied to technology-upgrade investment for factories retrofitting existing production lines.
Layered on top is a government-guided investment fund system, instructed in section sixteen to play a stronger role steering private capital toward designated sectors, and the future-industries risk-sharing mechanism in section eight that functions as a state-backed buffer against capital losses for early investors in embodied intelligence. Put together, a Chinese robot maker's research spending is subsidized, a Chinese factory's decision to buy that robot is subsidized, and the venture capital funding the next generation of embodied-AI startups is partially insured by the state. Beijing is now underwriting both ends of the robot adoption curve at once, paying down the manufacturer's development cost and the buyer's purchase risk inside the same policy document, which flattens the payback-period math that normally makes automation a hard sell. None of that changes the underlying unit economics of a robot arm or a humanoid platform, but it does change who can afford to sell below cost and for how long, which is the number that actually matters when a Western buyer is comparing a landed quote from a Chinese integrator against a domestic or Japanese alternative.
Humanoid Robots Join the Smart-Terminal Category
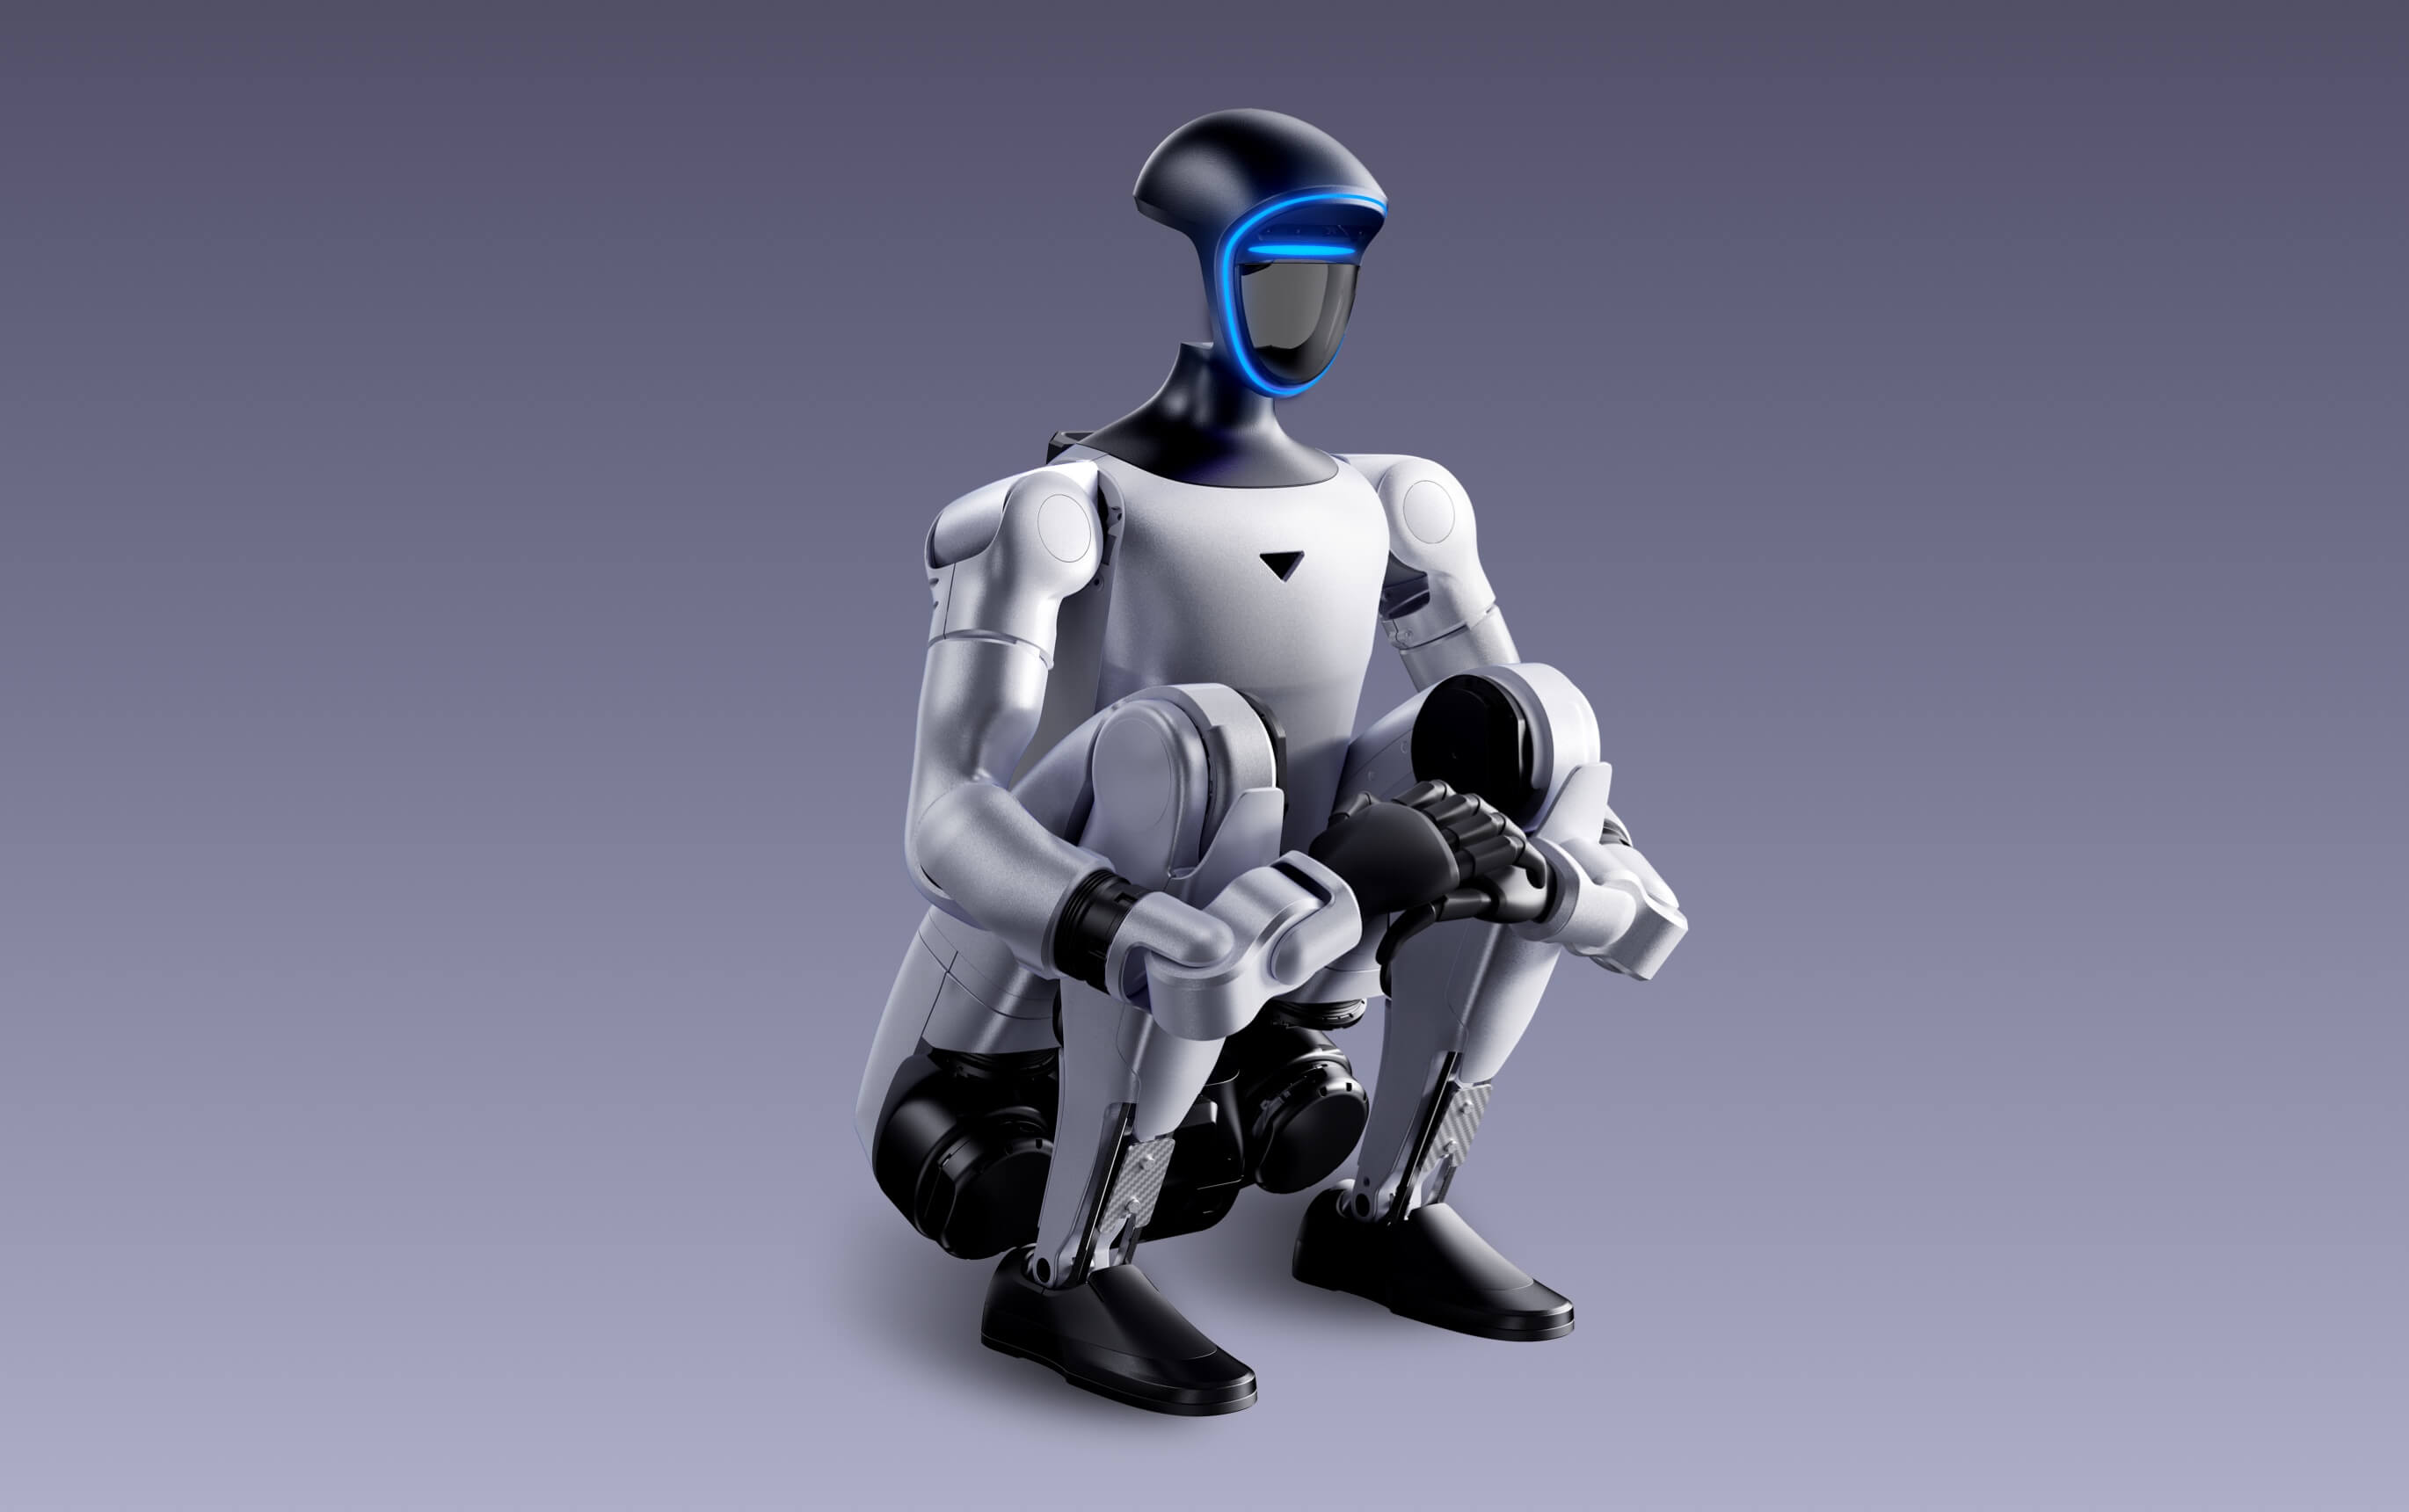
The decision to fold humanoid robots into the same AI-plus application-scenario program as smartphones and NEVs is a template choice, not an accident. China scaled NEV manufacturing from a niche export category to the world's largest fleet through exactly this combination: a named national priority, local-government procurement, city-level pilot fleets and production figures tracked by the NDRC. Applying the same playbook to humanoid robots signals that Beijing expects a similarly compressed timeline from prototype to volume order book. Treating a robot shipped into a Chinese factory, hospital or warehouse pilot as simultaneously a commercial transaction and a unit of national industrial capacity is Beijing's systematic conversion of automation into national power, and it is why foreign competitors should expect Chinese humanoid platforms to reach commercial volume faster than their balance sheets alone would justify.
For a Western buyer evaluating a Chinese humanoid robot vendor, the lesson from the NEV era is that price and delivery timelines will likely outrun independently verified performance data for a period, because the incentive structure built into this policy rewards scenario-deployment counts, pilots, placements and headline order books, as much as it rewards proven unit reliability.
Beijing's Own Warning About Its Own Investment Machine
The NDRC briefing contains an unusually direct caution that belongs in any sourcing risk assessment. Officials said the campaign must not become cover for destructive investment attraction, for localities blindly chasing trends into new projects, or for wasteful spending, and they warned against uniform industrial layouts that ignore a region's actual resource endowments, a direct reference to the duplicate construction that has already produced serial overcapacity in China's solar panel, battery and electric-vehicle industries.
That warning matters because robotics now carries the same policy label, new quality productive forces, that triggered those earlier waves of province-level subsidy competition. The practical read for procurement teams is to expect a similar sequence: a wave of provincial robotics and embodied-intelligence clusters chasing the designation over the next one to two years, aggressive early pricing as local governments compete to attract manufacturers, and a later consolidation phase once oversupply becomes visible, the same pattern that produced sharp price declines and eventual trade friction in solar modules and electric vehicles. Buyers locking in multi-year exclusive supply agreements with a single Chinese robotics vendor on the strength of today's pricing should treat that pricing as a policy artifact with a limited shelf life, not a durable cost curve.
The Standards Fight Behind the Self-Reliance Mandate
Two further instructions point at the component supply chain specifically. Section seventeen tells free trade pilot zones to pull in advanced production factors, domestic and foreign, based on their location, resource endowments and industrial strengths, and separately encourages international standards organizations to establish operations inside China. At the same briefing, NDRC officials repeated the now-familiar line that core technologies cannot be asked for, bought, or begged for, the standard framing Beijing uses to justify accelerated domestic substitution of imported components.
Read together, those two instructions point in the same direction from opposite ends. China wants the bodies that write the technical rules for robotics interoperability and safety to operate on its own soil, giving it more influence over standards that foreign integrators eventually have to comply with, while simultaneously pushing domestic robot makers to replace the imported precision reducers, servo drives and sensors that remain the most import-dependent parts of a Chinese-made robot's bill of materials. For component suppliers in Japan, Germany and the United States, near-term revenue from Chinese robot makers probably holds up, since substitution takes years to reach high-precision parts, but the multi-year trajectory of that relationship is now explicit government policy rather than a market-driven contingency.
What Changes for Sourcing Decisions Before the Policy Takes Effect
Three practical conclusions follow directly from the document and the briefing. First, pricing on conventional robot hardware and automation retrofits sourced from China is likely to keep falling faster than component and labor costs alone would predict, because both the manufacturer's research spending and the buyer's adoption decision are being subsidized in the same policy cycle. Second, humanoid robot platforms from Chinese vendors will reach commercial pilots and headline order announcements on a timeline set by industrial policy rather than by independently verified reliability data, which means procurement teams should weight pilot results and third-party testing more heavily than vendor-reported deployment counts. Third, the NDRC's own warning about duplicate construction is the clearest signal available that today's aggressive quotes from newly subsidized robotics clusters are not a stable baseline, and contracts written against them should include repricing or volume-flexibility clauses rather than long fixed terms.
Beijing has now written robotics, humanoid platforms and embodied intelligence into the same policy architecture that already reshaped global solar panels, batteries and electric vehicles, complete with the subsidies that drove those industries' rapid cost declines and the same official acknowledgment that overbuilding is the predictable side effect. A buyer who treats this document as background noise will be negotiating against a cost structure they do not understand; a buyer who treats it as the opening move in a multi-year pricing and capability shift will negotiate from a stronger position.
This analysis synthesizes government policy statements and public market activity as of the stated information cutoff.
This article is provided for general information purposes only and does not constitute investment, procurement, legal, or engineering advice. Figures reflect the sources listed above as of the stated information cut-off and may change without notice.