China's Humanoid Tenders Tripled in September. The Market Still Isn't Real Yet.
China's government procurement of humanoid robots jumped 168% to US$39M in September, but shrinking average deal sizes reveal a market still dominated by training labs and demonstrations, not factories.

China's Humanoid Tenders Tripled in September. The Market Still Isn't Real Yet.
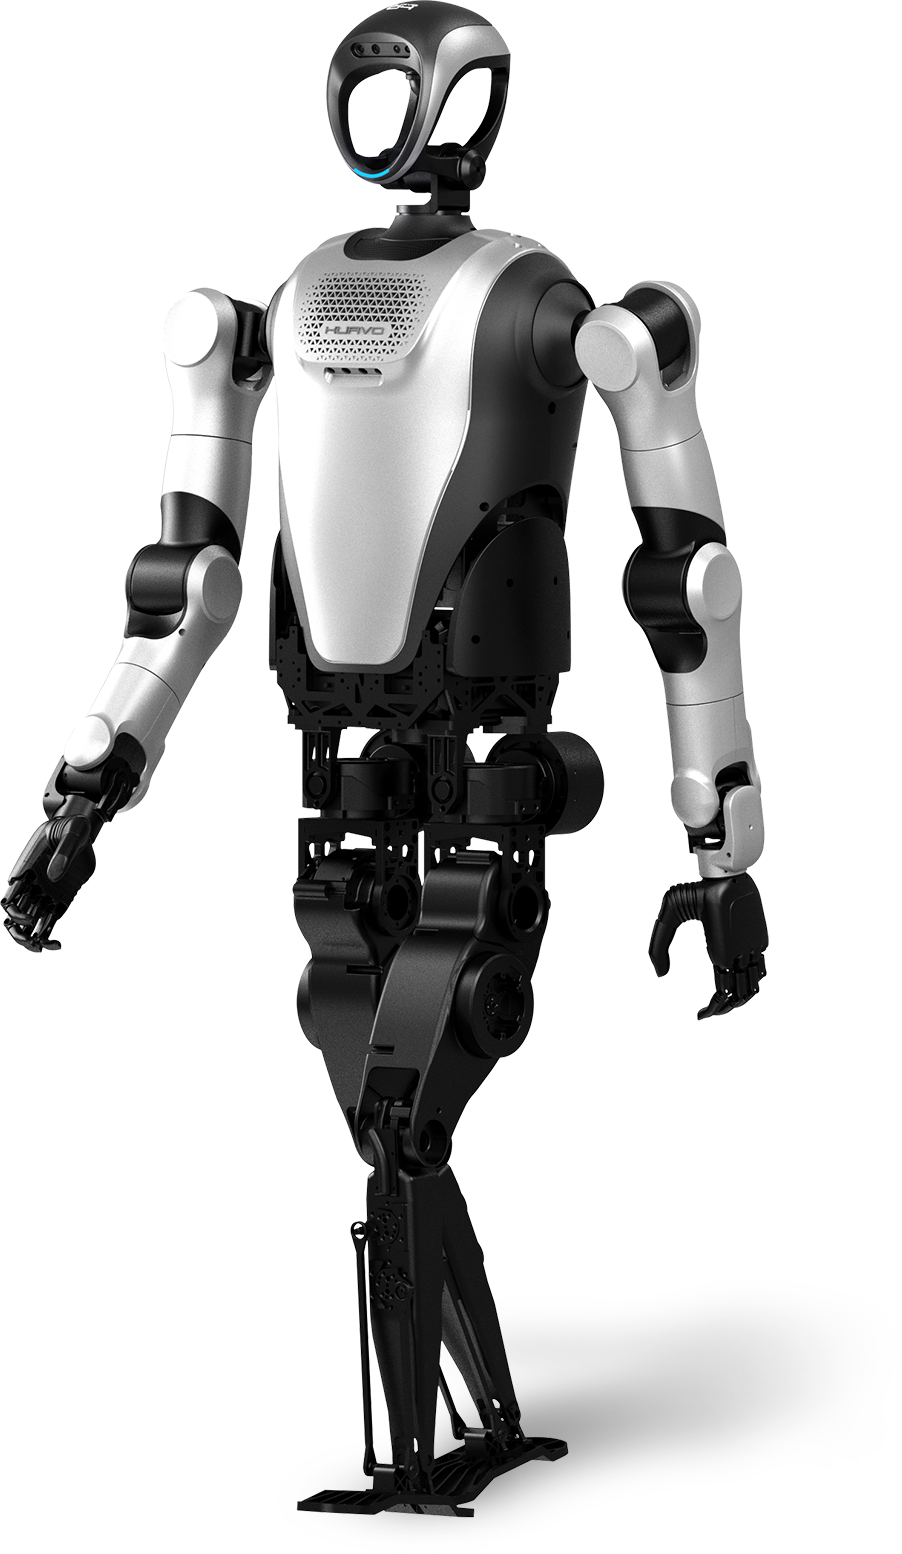
China's government and institutional buyers spent RMB 284 million, approximately US$39 million, on humanoid and mobile-robot tenders in September 2026, across 78 publicly disclosed projects, according to data compiled by the Humanoid Robot Scene Application Alliance and published by the China Mobile Robot Industry Alliance (CMRA) on October 20. That figure is up 168 percent from August's RMB 106 million, approximately US$14.6 million. Unitree, UBTECH, and Leju Robotics won the highest-frequency bids. The average deal size, however, fell to roughly RMB 3.9 million (about US$540,000), down from a June peak of RMB 19.17 million (about US$2.63 million), a pattern that points to a handful of large platform orders inflating the headline total rather than a broad new wave of industrial buying.
Leju Robotics, the least internationally known of the three leading winners, is a Shenzhen-based humanoid maker founded in 2016, with branches in Harbin and Hangzhou. Its Kuavo line spans a general-purpose bipedal platform, an education-focused AELOS series, and a hospital-logistics robot called Fluvo; the company raised roughly US$29 million in a pre-IPO round reported in October 2025 backed in part by Tencent. Where Unitree and UBTECH compete partly on consumer-adjacent brand recognition, Leju has built its order book inside vocational classrooms and public-sector demonstration budgets, exactly the buyer segment this month's tender data describes.
The buyers tell the real story. Universities and vocational schools accounted for the bulk of September's volume, mostly for training labs and secondary-development kits. Government and public institutions, including local Development and Reform Commission offices, emergency-management bureaus, and science museums, bought for displays, safety-inspection pilots, and innovation showcases. K12 schools in cities including Shenzhen and Wuxi made smaller purchases. Most line items were labeled "humanoid robot development platform" or "embodied AI training platform," procurement language that describes a research tool, not a production asset. A smaller share went to public displays and to genuine industrial uses such as substation inspection.
A Tender Market Built on Training Budgets, Not Production Lines
The distinction matters because it separates two narratives that get conflated in humanoid coverage: capital markets betting on future manufacturing deployment, and a present-day government procurement cycle that is mostly funding classrooms and demo floors. CMRA's own analysis is blunt about which one September represents. The data excludes K12 desktop devices, construction-linked purchases, micro-leasing contracts under RMB 100,000 (about US$13,700), and five undisclosed deals, so the true volume of small-ticket activity is likely higher than the headline RMB 284 million suggests. Even with that undercount, the alliance's conclusion is that normalized, large-scale industrial and commercial procurement "has not yet become mainstream."
That conclusion sits awkwardly next to the month-over-month growth rate. A 168 percent jump reads, at a glance, like inflection-point evidence. The deal-size data argues the opposite: September's total was pulled up by a small number of bulk platform orders, the same mechanism that produced June's RMB 19.17 million average before it collapsed to RMB 1.63 million (about US$224,000) in August. Buyers who procure humanoid platforms for teaching labs tend to order in batches tied to semester cycles and annual budget allocations, which makes month-over-month swings in this data closer to seasonal noise than to a demand-curve signal. A procurement team evaluating humanoid suppliers based on headline Chinese government spending figures should treat any single month's total as close to meaningless without the average-deal-size context underneath it.
Why Three Names Keep Winning the Same Tenders
Unitree, UBTECH, and Leju's dominance of high-frequency bidding is not an accident of brand strength. All three have spent the past two years building dedicated education and government-procurement product lines, pre-packaged bundles of hardware, a development software kit, and curriculum materials, aimed squarely at the university and vocational-school buyer. That is a different sales motion from courting a factory operations director, and it rewards a different kind of company: one with a catalog product a procurement office can cite directly in a tender document, rather than one requiring a bespoke integration project. Smaller or newer humanoid makers without an existing education-channel product are effectively locked out of this specific tender pool, regardless of how capable their hardware is, because they have nothing a school purchasing office can order off a list.
This is also why the September total should not be read as a market-share scoreboard for China's humanoid sector broadly. Companies pursuing warehouse, logistics, or manufacturing-integration deals, the use cases that would actually validate commercial-grade reliability, largely do not show up in this tender data at all, because those deals are negotiated directly with enterprise buyers rather than disclosed through public tender portals. The CMRA figures capture one specific, visible slice of demand: public-sector and education spending that is procured transparently. It is a useful early-warning indicator for which brands are winning institutional mindshare, but it says comparatively little about which humanoid platforms are closest to surviving a real production floor.
How This Compares to Buying Patterns Outside China
The pattern is not unique to China, but the scale and state sponsorship are. In the United States and Europe, early humanoid pilots have tended to originate with individual enterprise customers negotiating narrow, task-specific trial deployments directly with a handful of well-capitalized suppliers, arrangements closer in spirit to a commercial proof-of-concept contract than to a standardized tender. China's model instead runs the procurement process through thousands of discrete public-sector budget lines, each small enough to clear local approval thresholds without the scrutiny a single large industrial contract would attract. That structure makes the Chinese market look, in aggregate dollar terms, far larger and more active than it is on a per-buyer basis, since a single province's education bureau distributing humanoid kits across a dozen vocational schools can generate more disclosed transaction volume than one real factory pilot elsewhere. Reading the two markets on the same chart without this context overstates how far ahead Chinese commercial adoption actually is.
What a Procurement Buyer Should Actually Take From This
For a buyer evaluating whether China's humanoid sector has reached commercial maturity, the September data offers a specific, falsifiable answer: not yet, and the government's own procurement behavior is the evidence. State and institutional buyers are themselves still purchasing these machines as training and demonstration tools rather than as line-ready equipment, which undercuts any supplier pitch that leans on government adoption as proof of industrial readiness. A vendor citing strong Chinese tender volume as a commercial-maturity signal is, in most cases, citing classroom and museum procurement, not factory procurement. The distinction between a demo and a deployable system is not a philosophical point here; it is the literal difference between the roughly US$540,000 average training-lab order in these figures and the kind of multi-year industrial services contract that would actually validate a platform for continuous production use.
The deeper pattern connects to a dynamic already visible in Beijing's provincial robot-counting and subsidy programs: public money is building adoption infrastructure, demonstration pipelines, trained operators, curriculum, standardized procurement language, well ahead of the industrial use cases those pipelines are meant eventually to serve. That is a defensible industrial-policy sequencing choice, and it mirrors the gap between demo performance and deployment reality that recurs across humanoid markets outside China as well. But it means the 168 percent September growth figure should be read as evidence of how aggressively China's state apparatus is building a humanoid-literate workforce and institutional base, not as evidence that humanoid robots are close to paying for themselves on a factory floor. Whether this funding pattern signals durable momentum or an early peak in institutional enthusiasm will depend on whether 2027's tender data starts showing genuine industrial-deployment line items rather than more training platforms, a test the current numbers have not yet passed.
A buyer sourcing components, integration services, or competitive intelligence against Unitree, UBTECH, or Leju should weight this data accordingly: strong tender volume confirms which brands have captured China's education and government-demonstration channel, a real and valuable asset for long-term market positioning, but it confirms nothing about field reliability, mean time between failures, or total cost of ownership under continuous industrial use. Those answers will come from enterprise deployment data that, by its negotiated and private nature, does not appear in a public tender database at all.
The sharpest number in this data set is not the RMB 284 million (about US$39 million) headline. It is the fall in average deal size, from RMB 19.17 million (about US$2.63 million) in June to RMB 3.9 million (about US$540,000) in September, a collapse that says China's humanoid tender market grew louder in the third quarter without growing up, and procurement teams would do well to watch the deal-size trend line, not the monthly total, before drawing conclusions about how close any single supplier is to industrial-scale readiness.
This article is provided for general information purposes only and does not constitute investment, procurement, legal, or engineering advice.
This analysis synthesizes industry-association procurement data and public tender records.