
Budgeting for an AMR and AGV: Current Market Prices Explained
A mid-range Chinese autonomous mobile robot that cost RMB 100,000 to RMB 150,000 (about USD 14,000 to USD 21,000) in 2020 now ships for roughly half that, while Western list prices have barely moved. Post 4 of our AMR/AGV foundations series turns that spread into a working budget: current price bands for every major vehicle class from USD 40,000 flat-platform units to USD 300,000 autonomous forklifts, the structural forces behind the China versus global gap, the five cost drivers that explain any quotation, and the ARPI Price Architecture Map, our original benchmark reference for a market with no audited price index.
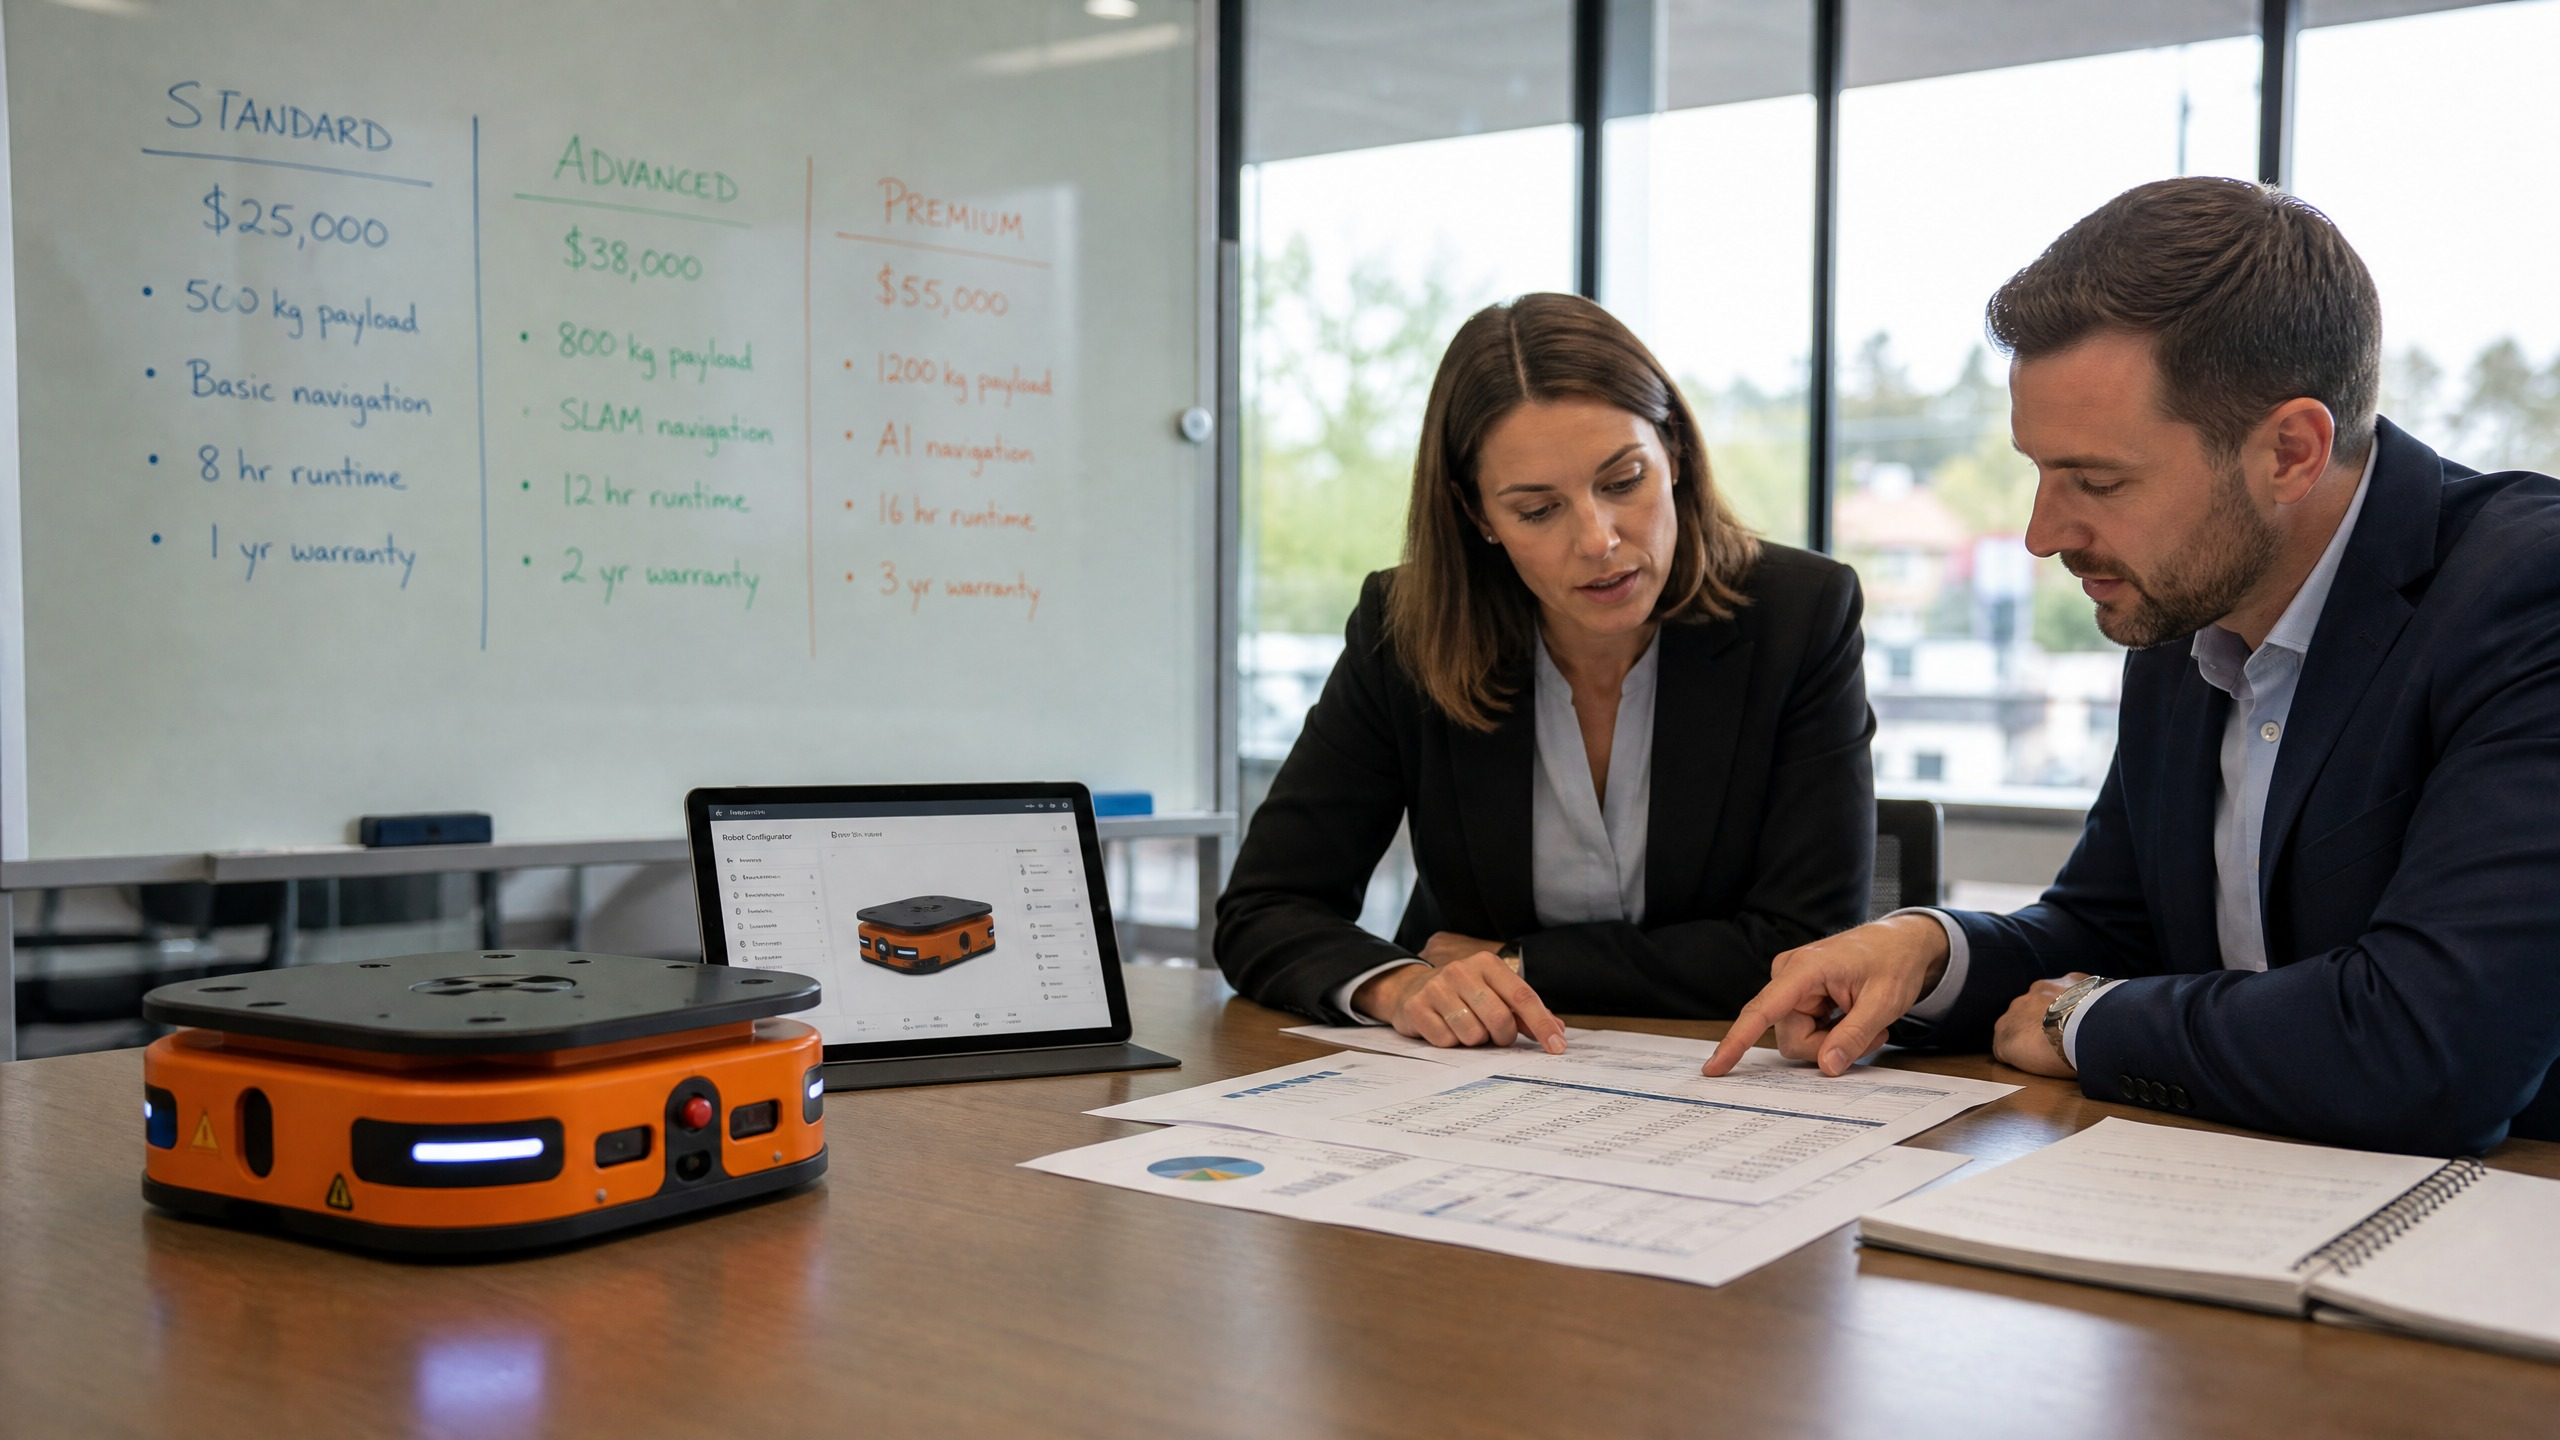
The most useful thing a first-time buyer can learn about mobile robot pricing is that the sticker price of the vehicle is the least stable number in the entire project. A mid-range autonomous mobile robot (AMR) that left a Chinese factory for roughly RMB 100,000 to RMB 150,000 (about USD 14,000 to USD 21,000) in 2020 now ships for RMB 50,000 to RMB 80,000 (about USD 7,000 to USD 11,200), a decline of 40 to 50 percent in five years, according to the Faxiangongchang Industrial Research Institute's 2026 report on China's mobile robot industry. Over the same period, Western list prices have held far firmer, with entry flat-platform AMRs still quoted at USD 40,000 to USD 80,000 per unit in the most recent financing-market data. That widening spread, not any single price point, is the real story of this market, and it shapes every budgeting decision that follows. This guide, the fourth in our ten-part series on AMRs and automated guided vehicles (AGVs), lays out the current price bands by robot class, explains the China versus global gap, identifies what actually drives cost, and projects where pricing is heading.
Price Range by Subcategory
Mobile robot pricing is best understood by vehicle class rather than by brand, because the spread between classes is far wider than the spread between competing vendors within a class. Drawing on the class taxonomy we established in Tuesday's article, the market in mid-2026 clusters into four broad price tiers.
At the entry level sit flat-platform and under-ride AMRs, the workhorses of goods-to-person picking and light transport. In Western markets these typically purchase for USD 40,000 to USD 80,000 per unit, according to deployment data published in May 2026 by CHG-MERIDIAN, a global technology financing provider, with 48 to 60 month leases running USD 600 to USD 900 per unit per month. Tugger and towing AGVs, which pull carts along defined routes, occupy a similar band at USD 50,000 to USD 85,000, with leases of roughly USD 800 to USD 1,200 monthly.
The step change comes with lifting. Forklift AGVs that handle pallets and racking span USD 75,000 to USD 200,000 depending on lift height, payload, and navigation complexity, and lease for USD 1,200 to USD 3,200 per month. At the top of the range, complex autonomous forklifts that combine natural navigation with high-payload lifting start at USD 150,000 and can exceed USD 300,000, with monthly lease payments of USD 2,200 to USD 5,500. Heavy-load AGVs built for automotive plants, shipyards, and foundries, carrying 5 to 60 tonnes, are custom-engineered projects priced case by case and rarely quoted publicly at all.
One budgeting rule should be applied to every figure above: hardware is only part of the invoice. For every dollar spent on the vehicle itself, buyers should plan roughly 30 percent more for engineering, solution design, site mapping, fleet software setup, safety validation, and commissioning. A single USD 50,000 AMR carries an estimated five-year total cost of ownership of about USD 84,000 once maintenance, software licensing, and energy are included, a 68 percent premium over the purchase price. Readers of our collaborative robot series will recognise the pattern: in mobile robotics, as in fixed-arm automation, the sticker is the entry fee, not the bill.
China vs Global Price Gap
The single largest pricing variable in this market is geography of manufacture. Chinese AMRs are currently priced at roughly 40 to 60 percent of equivalent European and American products with broadly comparable core functionality, according to the Faxiangongchang institute's analysis. In concrete terms, a mid-range Chinese AMR with a payload under one tonne now leaves the factory at RMB 50,000 to RMB 80,000 (about USD 7,000 to USD 11,200), while the comparable Western flat-platform unit purchases at USD 40,000 to USD 80,000. Even after freight, duties, integration, and local support are added, the landed cost gap remains substantial.
Three structural forces sustain the gap. First, component localisation: domestic Chinese lidar suppliers and controller makers have collectively reduced the hardware cost structure of Chinese mobile robots by roughly 35 percent since 2022, and those savings flow directly into ex-factory pricing. Second, scale: Hikrobot alone disclosed in July 2026 that it has produced more than 200,000 mobile robots, with its newest manufacturing base rated at 75,000 units per year, while Geek+ has delivered around 56,000 AMRs to roughly 40 countries. Volume of that order amortises fixed engineering costs in a way no Western AMR maker can currently match. Third, competitive intensity: nearly 100 new mobile robot products were launched globally in the first half of 2026, and about four in five came from Chinese companies, a supply-side crowding that pressures every incumbent's price list.
The gap is reshaping trade flows. China's mobile robot export order ratio has climbed from about 26 percent in 2022 to more than 40 percent in 2025, meaning the price differential is no longer a domestic Chinese phenomenon but an active force in European, Southeast Asian, and North American procurement. Buyers should note the caveat we apply throughout this series: lower ex-factory price does not automatically mean lower total cost, because local service coverage, spare parts logistics, software maturity, and integration support all sit outside the sticker and can erode the gap in practice. What the gap reliably delivers is negotiating leverage, since every Western quotation is now implicitly benchmarked against a Chinese alternative.
What Drives the Price
Understanding why one mobile robot costs USD 45,000 and another USD 250,000 requires unpacking five cost drivers, in descending order of impact.
Payload and lifting capability dominate. Moving from a 500-kilogram platform to a pallet-lifting forklift configuration multiplies structural, motor, and hydraulic content, which is why the forklift AGV band starts roughly where the flat-platform band ends. Navigation stack comes second. A magnetic-tape AGV following a fixed guide path carries minimal sensing, while a natural-navigation AMR fuses lidar, depth cameras, and inertial sensors with simultaneous localization and mapping (SLAM) software; laser SLAM systems now account for about 42.5 percent of the navigation market by revenue, and the sensing package alone can represent several thousand dollars of bill-of-materials cost, though that share is falling fast as Chinese lidar volume scales.
Third is software and fleet management. The fleet management system that allocates tasks, plans paths, and prevents deadlocks is often licensed separately, and its quality matters more as fleets grow: with more than 200 robots in one facility, scheduling algorithm differences alone can swing overall system throughput by 10 to 30 percent. Fourth, safety certification: compliance with ISO 3691-4, the international standard for driverless industrial trucks, and ANSI/RIA R15.08, the American standard for industrial mobile robots, adds testing, redundant sensing, and documentation cost that uncertified products avoid, which is one reason unusually cheap units deserve scrutiny. Fifth, integration depth: connecting robots to warehouse management systems, conveyors, doors, and lifts is engineering labour that scales with project complexity, which is why deployment cycles run three to six months for standard projects and 12 to 18 months for large custom programmes.
Price Trend
Every current signal points the same direction: downward on hardware, flat to upward on software and services. The 40 to 50 percent five-year decline in Chinese mid-range AMR pricing is the clearest data point, and the structural forces behind it, component localisation, manufacturing scale, and crowded competition, are strengthening rather than fading. The first half of 2026 brought the largest wave of new product launches the industry has recorded, and history in adjacent robot categories shows launch waves precede price competition.
Two counterweights deserve attention in any multi-year budget. The first is trade policy. The United States opened a Section 232 national-security investigation into robotics imports in 2025, and any resulting tariffs would raise landed costs for Chinese-manufactured robots in the American market without changing ex-factory economics, a scenario risk we flagged in our collaborative robot coverage that applies with equal force here. The second is the migration of value into software. As hardware commoditises, vendors are shifting margin into fleet management licences, RaaS (robots-as-a-service) subscriptions, and support contracts. The robots-as-a-service model, which the International Federation of Robotics (IFR) reports grew 42 percent in 2024, converts capital expenditure into a recurring fee and is attractive for pilots, but over a five-to-seven-year horizon a subscription can cost more than ownership, so the pricing question increasingly becomes a financing question. Buyers negotiating today should assume the hardware they are quoted will be cheaper next year, and should push for contract structures, whether lease, RaaS, or staged purchase, that let them capture some of that decline rather than locking peak pricing for a full depreciation cycle.
Benchmark Reference
No audited, industry-wide price index yet exists for mobile robots, and no manufacturer in this asset class discloses per-unit pricing in its regulatory filings, so this publication maintains its own benchmark references built from named, dated sources. The table below is the ARPI Price Architecture Map, our original synthesis of the evidence assembled for this article. For each major vehicle class it aligns the Western purchase band, the Chinese ex-factory band where documented, the dominant cost driver, and the direction of travel. Its method is deliberate triangulation: Western bands come from 2026 financing-market deployment data, Chinese bands from the Faxiangongchang institute's 2026 industry report, and scale context from manufacturer disclosures by Hikrobot and Geek+ and from IFR installation data. Its limitation is equally deliberate and stated plainly: these are directional ranges from named research and vendor sources, not audited transaction data, and unlike company disclosures they cannot be treated as directly comparable across scope boundaries. Actual quotations vary with volume, configuration, integration depth, and negotiating position.
Table 1: The Price Architecture Map
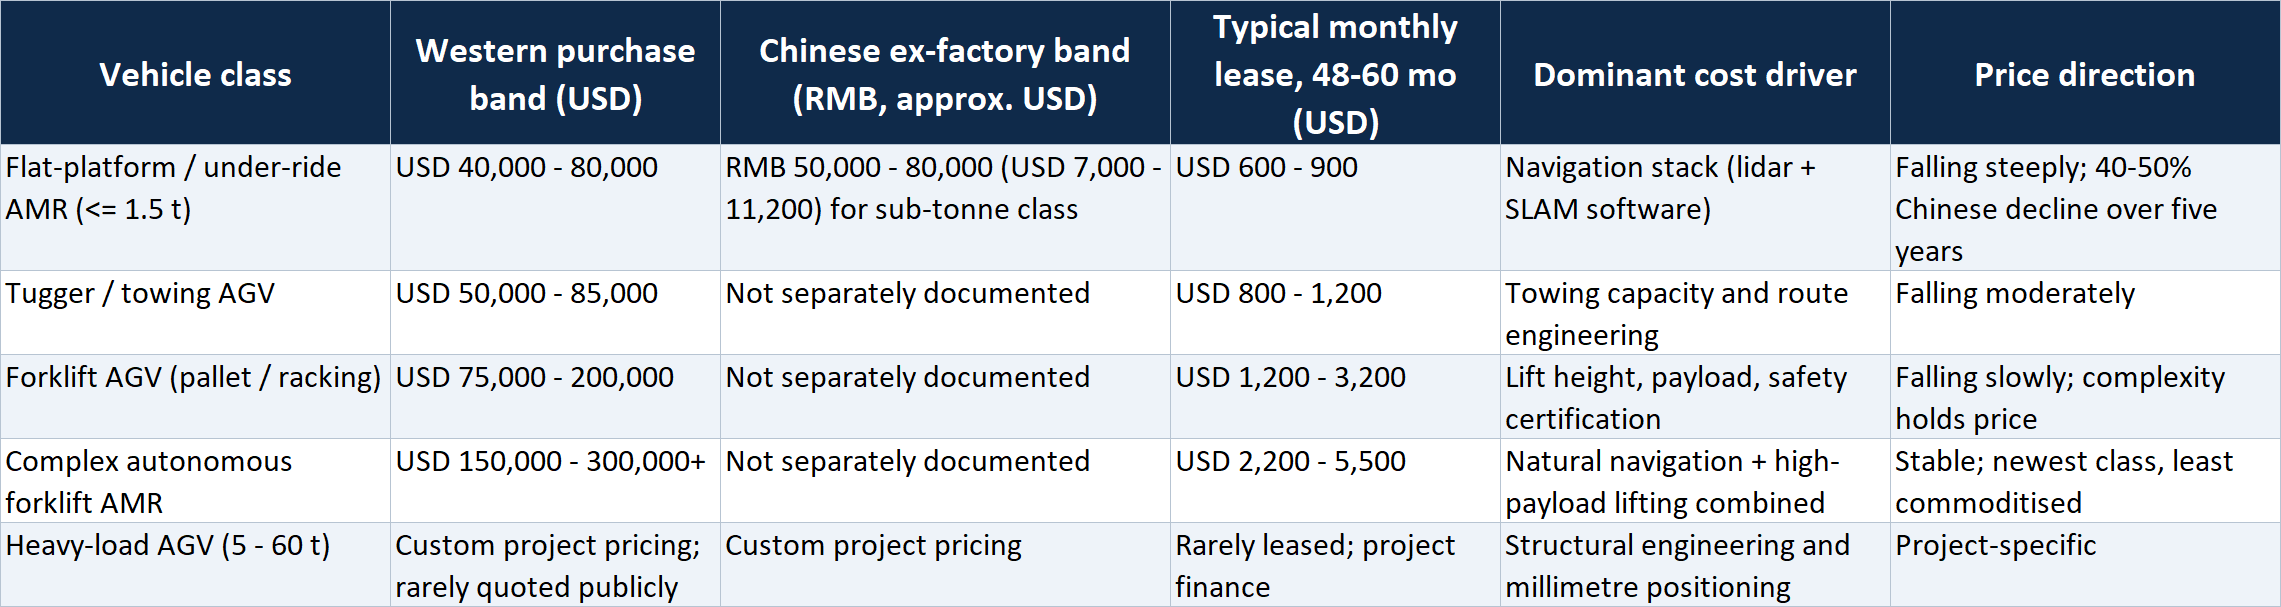
Original synthesis: Western purchase and lease bands from CHG-MERIDIAN deployment data (May 2026); Chinese ex-factory band and five-year decline from the Faxiangongchang Industrial Research Institute report (June 2026); RMB converted at an indicative RMB 7.15 per USD. Directional ranges from named sources, not audited transaction data; actual quotations vary with volume, configuration, integration depth and negotiation.
For budget planning, we suggest anchoring on three reference figures. A pilot deployment of three to five entry AMRs in a Western market, fully implemented, should be budgeted at roughly USD 200,000 to USD 500,000 over five years. A mid-scale fleet of ten mixed units can exceed USD 1 million in five-year commitment before implementation extras. And any quotation for a sub-tonne AMR that lands far below USD 30,000 in a Western market, or far above RMB 100,000 ex-factory in China, deserves a direct question about what is included, because the documented bands say one of you is missing something.
Table 2: Budgeting a First Deployment, the ARPI Build-Up Method
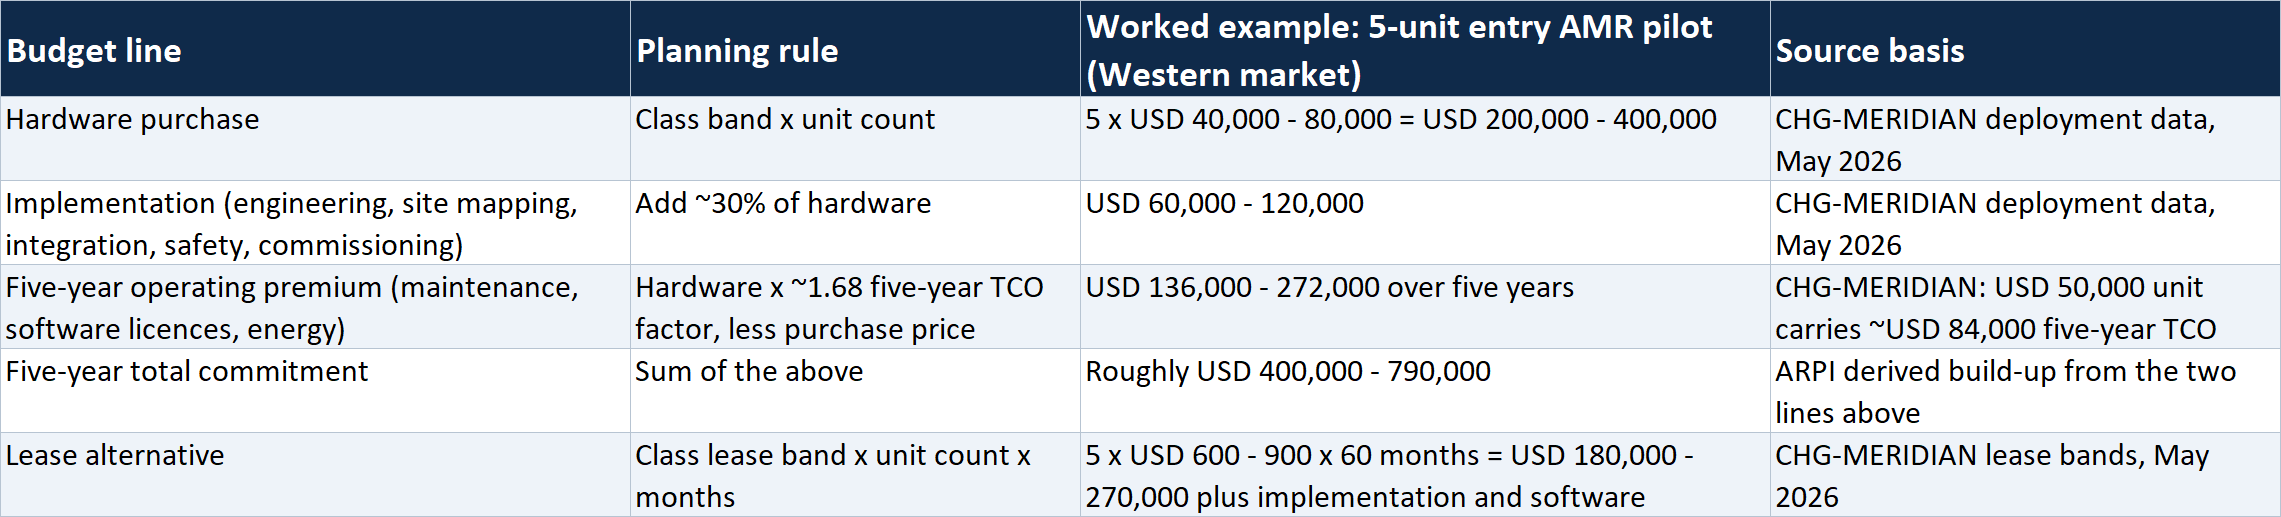
A worked planning example, not a quotation. The five-year TCO factor is an estimate for a mid-range Western AMR and varies with duty cycle, software stack and service contract. Chinese-manufactured units can lower the hardware line materially but may shift cost into freight, duties, integration and local support.
The Bottom Line
Mobile robot pricing in 2026 rewards buyers who treat the market as two linked but distinct systems: a hardware market where Chinese scale is driving prices down 8 to 10 percent a year on trend, and a software-and-services market where vendors are rebuilding their margins. Budget for the full architecture, hardware plus roughly 30 percent implementation plus recurring software, benchmark every Western quotation against the documented China bands, and structure contracts to capture the price decline that every current signal says is still running. Tomorrow, in the fifth article of this series, we turn from prices to the people behind them, with a scope-adjusted ranking of the manufacturers that dominate this market.
Disclaimer
This article is provided for general information only and does not constitute procurement, financial, or investment advice. Price ranges are directional estimates drawn from named industry research and vendor financing sources current as of 29 July 2026; they are not audited transaction data, and actual quotations vary with volume, configuration, integration scope, and negotiation. Figures originally reported in Chinese yuan (RMB) are accompanied by approximate US dollar (USD) equivalents converted at an indicative rate of RMB 7.15 per USD. Readers should verify current pricing directly with vendors before making purchasing decisions.














