
Inside the $46,000 Humanoid Robot: A Full BOM Teardown of China's Cost Advantage
Morgan Stanley estimates a humanoid robot built on the Chinese supply chain costs $46,000 to manufacture in 2025–2026, versus nearly $130,000 using non-Chinese components. This teardown breaks down where every dollar goes — and why actuation, not software, is the defining battleground.
The $46,000 Robot: What the Bill of Materials Actually Reveals
The single most important number in humanoid robotics right now is not a robot's walking speed, payload capacity, or AI benchmark score. It is $46,000 — Morgan Stanley's 2025 estimate for the bill of materials cost of a humanoid robot built entirely on the Chinese supply chain. The equivalent figure for a robot built without Chinese components: nearly $130,000.
That $84,000 gap is not a rounding error. It is a structural cost advantage that shapes every pricing decision, every investment thesis, and every procurement conversation in the industry. Understanding where it comes from requires opening the robot and looking at what is inside.
What Drives Cost Inside a Humanoid Robot
A mid-range industrial humanoid robot — the kind being deployed in Chinese factories and logistics centers in 2026 — has a total BOM cost of roughly $40,000 to $80,000 depending on capability level and production volume. The cost is not distributed evenly across systems.
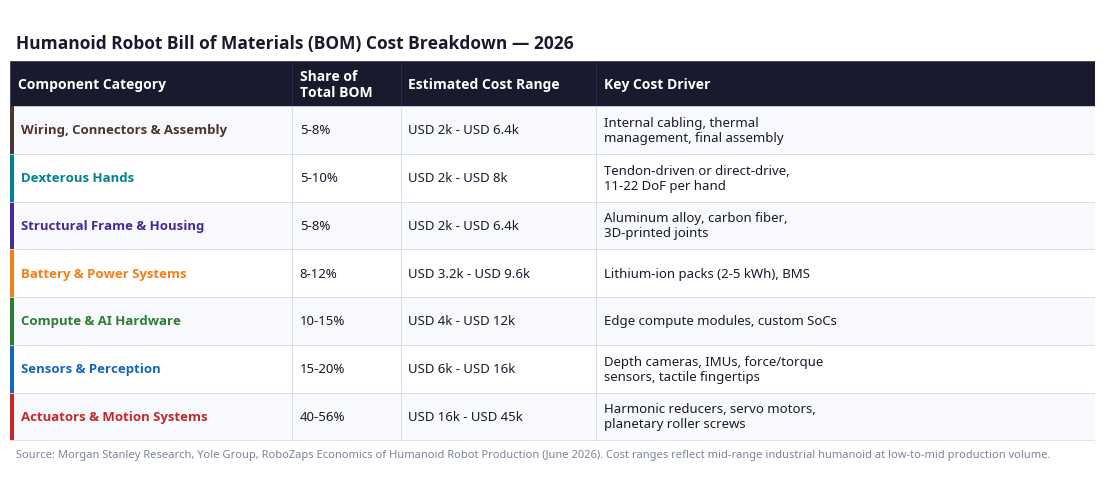
Actuation — the motors, reducers, and transmission screws that make the robot move — is the dominant cost item at every capability level. A full-size humanoid requires 28 to 44 actuators in the body alone, plus up to 50 actuators in the hands for advanced dexterity configurations. Each body actuator combines a motor, a precision gearbox (harmonic drive or planetary), an encoder, and a torque sensor. At low production volumes, high-torque hip and knee actuators cost $500 to $2,000 each.
Where China's Cost Advantage Is Concentrated
The $84,000 cost gap between Chinese and non-Chinese supply chains is not spread evenly across the BOM. It is concentrated in three categories: harmonic reducers, servo motors, and battery systems.
Harmonic reducers are the most price-sensitive item. Chinese manufacturers including Suzhou Green Harmonic Transmission Technology, Ningbo ZD Leaderdrive, and Zhejiang FORE Intelligent Technology are quoting 30% to 40% below Japanese incumbents Harmonic Drive Systems and Nabtesco. A robot using 15 harmonic reducers saves $1,500 to $4,500 per unit by sourcing domestically in China versus importing from Japan.
Servo motors and frameless torque motors follow a similar pattern. Chinese motor manufacturers benefit from the same supply chain infrastructure that built China's electric vehicle industry — rare earth magnet processing, copper winding automation, and precision bearing production are all mature domestic capabilities.
Battery systems represent the third major differential. Chinese battery manufacturers, led by CATL and BYD's supply chain ecosystem, produce lithium-ion packs at costs that Western and Japanese manufacturers cannot currently match at equivalent quality levels.
The Reliability Question the BOM Does Not Answer
A teardown of costs reveals where the price gap comes from. It does not answer whether the cheaper components perform as well over time. This is the honest constraint that most coverage of Chinese manufacturing advantages skips.
Japanese harmonic reducer manufacturers cite 50,000-hour mean-time-between-failure data accumulated over decades of industrial robot deployments. Chinese Tier 1 reducer manufacturers are producing components that perform adequately in early humanoid deployments — but "adequate in early deployment" and "proven over 50,000 hours" are not the same claim. The 10,000-unit Chinese government deployment mandate for 2026 will generate more field hours for Chinese reducers than the entire previous decade of humanoid testing combined. The reliability question will be answered by that data, not by specification sheets.
The Bigger Signal
The humanoid robot BOM is following the cost compression curve of every previous Chinese manufacturing wave: enter at lower price points, capture volume, reinvest in capacity, and compress margins until quality catches up with incumbents. Solar panels, lithium batteries, and drone components all followed this pattern. The actuator market is now at the same inflection point those industries reached approximately five years before commoditization.
"The humanoid robot BOM is not a technology story. It is a manufacturing economics story — and China is writing the same chapter it wrote for batteries, solar, and drones."
For procurement teams, the practical implication is straightforward: a robot priced identically by two manufacturers can carry materially different long-term maintenance cost profiles depending on whether its reducers are Japanese Tier 1 or Chinese Tier 2. Price is visible at purchase. Reliability cost is visible at year three.














