
AI Robotics and ESG: Green Solution or Just Better-Looking Waste?
Robots promise efficiency. But does efficiency actually mean sustainability — or just better-looking waste?
You are staring at a monthly energy invoice that just crossed a number you didn't budget for. Your factory is producing more than ever. Scrap rates are down. Your ESG dashboard looks clean — fewer rejects, lower rework, the waste bins genuinely emptier than they were eighteen months ago. The sustainability slide in last quarter's board deck practically wrote itself. Then the facilities manager walks in and asks if you noticed the power consumption trend. You hadn't. The robots are running beautifully. And they are hungry.
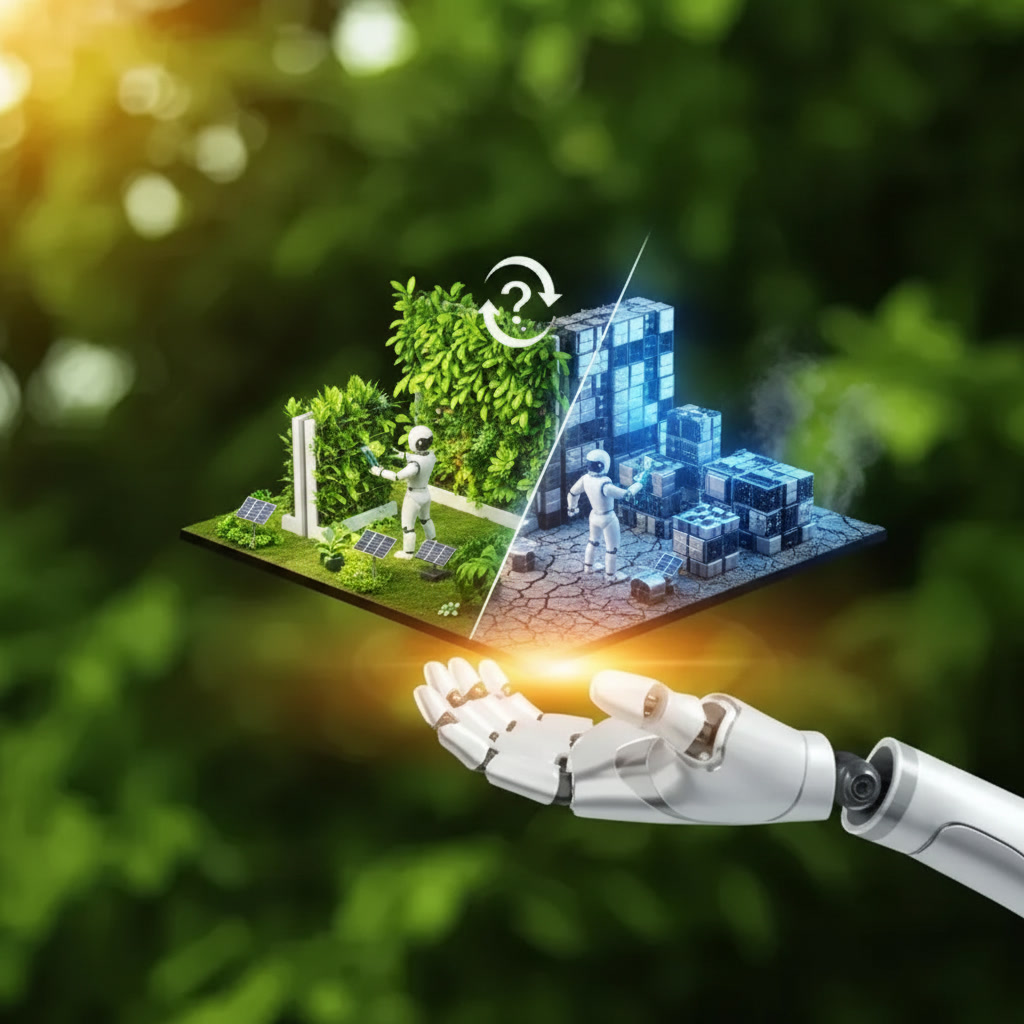
This is the hidden friction of deploying AI robotics at scale. Most companies that automate for sustainability fix one visible problem — physical waste on the factory floor — while quietly creating a second one that doesn't show up until the energy bill lands or the hardware refresh cycle hits. If you are making robotics investment decisions based on scrap reduction alone, you are pricing in half the trade-off and reporting a fraction of the true cost. That gap, between what ESG dashboards show and what the full system actually costs, is closing fast — and regulators, investors, and supply chain partners are all starting to look behind the dashboard.
Do AI Robots Actually Improve Sustainability?
AI robots can improve sustainability — but only in specific parts of the system, and almost always with trade-offs somewhere else in the chain.
The clearest way to see this is to look at three regions making the same bet on automation at very different speeds and with very different energy grids behind them.
Global Data Pull:
- Asia: Asia accounted for 74% of all new industrial robot deployments globally in 2024, with 542,000 total units installed that year — more than double the count from a decade prior. (Source: IFR World Robotics 2025)
- Europe: Goldman Sachs Research estimates Europe faces a data centre pipeline of roughly 170 GW — equivalent to about one-third of the region's entire current electricity consumption — driven largely by AI workloads. (Source: Goldman Sachs Research, 2025)
- US: US data centre power demand accounted for approximately 4% of total US electricity in 2023, and is projected to more than double by 2030 as AI workloads scale. (Source: Goldman Sachs Research / RCR Wireless, 2025)
Asia is running the fastest and hardest. The International Federation of Robotics confirmed that Asia accounted for 74% of all new industrial robot deployments globally in 2024, with 542,000 units installed worldwide that year — more than double the total from a decade earlier. China alone is adding over 300,000 robots annually, a pace driven far more by competitive manufacturing pressure than by environmental targets. The energy grid powering that deployment is still heavily coal-dependent in many provinces, which means the robots are reducing physical waste at the factory gate while the power plant upstream is running hard to keep them online.
Europe is deploying more slowly but watching the energy problem arrive anyway — not from robot motors, but from the AI models sitting behind them. Goldman Sachs Research now estimates Europe faces an AI-driven data centre pipeline of roughly 170 GW, equivalent to approximately one-third of the continent's entire current electricity consumption. After fifteen years of declining power demand in the European energy sector, that figure represents a reversal that no ESG framework designed before 2022 anticipated. European companies face the sharpest tension here: the most rigorous sustainability regulations in the world, applied to a technology that is creating a new energy demand curve that those regulations were not written to manage.
In the United States, the picture is the starkest. US data centre power demand already accounted for approximately 4% of total American electricity in 2023, and Goldman Sachs projects that figure to more than double by 2030 as AI workloads scale. That growth will require an estimated $720 billion in global grid infrastructure investment just to keep pace. A company deploying AI-driven robots to reduce material waste by 8% may be contributing, indirectly, to a power grid under stress that will price electricity upward for everyone. The factory floor looks greener. The system behind it is running hotter.
What Does "Sustainable Robotics" Actually Mean?
Sustainable robotics is the practice of using automated systems to reduce the total environmental cost of a product across its entire life — not just the few seconds it spends being assembled.
Think about planning a long road trip to visit someone. You decide to pack efficiently: one bag instead of three, no unnecessary stops, a tight route. The car is loaded smartly. You feel organised. But if the vehicle gets twelve miles to the gallon and the nearest charging station is two hundred miles away, all that careful packing doesn't make the trip green — it just makes the inefficiency tidier. The trip still burns what the engine demands, and the engine is what matters. Sustainable robotics works the same way. A robot that reduces factory scrap by 15% is the well-packed bag. The AI model training it, the data centre cooling it, the rare earth magnets powering its joints, and the landfill receiving it in eight years — that is the engine. You can pack as efficiently as you like, but you have to reckon with what the engine costs.
"Asia accounted for 74% of all new industrial robot deployments globally in 2024 — but the energy grids powering that deployment are still dominated by fossil fuels in many regions, meaning the factory gets greener while the grid runs dirtier." (Source: IFR World Robotics 2025)
Precision became a proxy for green
In the early years of industrial automation, the equation was genuinely simple. A robot that didn't make mistakes didn't create scrap. Less scrap meant less material going to the bin. Less material in the bin meant a better environmental story. ESG reporting in manufacturing during this period was essentially a precision report with a green cover. The robots earned their sustainability credentials honestly, and the metrics that tracked them were straightforward: scrap weight, rework volume, reject rate. Those numbers went down. The dashboards looked good. Nobody was lying.
The energy debt arrived quietly
Then the AI layer landed on top of the hardware. The machines got smarter, faster, and dramatically more energy-intensive — not just in running their motors but in the computing layer required to train and update the models that made them smart in the first place. Goldman Sachs Research found that 60% of the increase in data centre electricity demand through 2030 is projected to be met by fossil fuel combustion, adding roughly 220 million tonnes to global carbon emissions. Training a single large AI model can consume as much energy as dozens of homes use in a year. The digital intelligence that makes a robot useful now has a physical weight that never appeared on a factory floor energy audit. Reporting precision metrics while ignoring compute costs became, quietly, the industry norm. The survival move here is to start measuring the compute cost of every efficiency gain — if an AI optimisation saves 5% in material but costs 10% more in energy, that is a loss the ESG report is currently hiding.
Circular design became the competitive floor
The companies that are getting this right are not just buying greener robots. They are redesigning their procurement criteria so that hardware can be modularly upgraded rather than wholesale replaced, and auditing the full lifecycle cost — sourcing of rare earth materials, energy consumption during training, and end-of-life disposal — before any purchase is made. The International Federation of Robotics identified sustainability as one of the top five robotics trends for 2025 precisely because supplier whitelisting now includes UN sustainability goal compliance in many industries. This is no longer a PR exercise. Losing a supplier relationship because your robot fleet's lifecycle footprint fails a customer's ESG audit is a direct revenue event. The robots that win in the next decade will be the ones whose total environmental cost has been designed and measured — not just their scrap output.
Is "Green Robotics" Just a Marketing Term — Or Is It a Survival Requirement?
Two genuine fears live inside this question, and both are held by rational people.
The first is that sustainability claims in robotics are mostly marketing noise — that companies are buying expensive automation, relabelling efficiency gains as ESG progress, and that nothing structurally different is happening for the planet. This fear is not wrong as a description of the current status quo. Most robotics sustainability reporting today is scrap-metric reporting with a new name. The energy cost, the material sourcing, and the end-of-life burden are largely invisible in published ESG numbers.
The second fear runs in the opposite direction: that robots are an environmental problem that should be slowed or regulated away, because the energy demand they generate — especially through AI compute — will outpace any material savings they produce. This fear has real data behind it. If AI data centre power demand doubles or triples by 2030 as projected, and 60% of that additional demand is met by fossil fuels, the carbon math is difficult to make work even with impressive factory floor scrap reductions.
Both fears are looking at real evidence. Neither is telling the complete structural story.
The hard truth is this: companies are not adopting robots because they want to be green. They are adopting robots because it is cheaper, faster, and more consistent than human labour at scale — and because their competitors are doing it. Sustainability only enters the calculation when it becomes a cost or a barrier. When energy prices rise enough that compute costs hurt margins, companies will optimise for energy efficiency — not because it is virtuous, but because it is survival. When major customers begin requiring full lifecycle ESG audits as a condition of supplier status — which is already happening in European automotive and electronics supply chains — companies will measure and manage the things they previously ignored. The rational survival choice is not to wait for that pressure to arrive. It is to build lifecycle cost accounting into robotics procurement now, before regulators or customers force an expensive retrofit. The companies that are doing this today are not the most ethical ones. They are the most commercially rational ones.
This development reinforces:
Who Owns Robot Data: The same operational data that creates ESG reporting risk also creates vendor lock-in risk — you can't manage what you can't access, and most companies don't own the data their robots generate.
Ethics & Governance: Sustainability doesn't happen because machines are efficient — it happens when rules make it mandatory, and the governance gap in robotics ESG is as wide as the one in data rights.
Where Robots are Used: The industries deploying robots fastest — automotive, electronics, logistics — are precisely the industries where full lifecycle ESG auditing is becoming a condition of doing business, not a bonus.
Robots don't decide what is sustainable. They are extremely good at scaling whatever system we have already accepted. If the system we accept runs on cheap coal and measured by scrap weight alone, robots will make that system faster and more efficient and call it progress. The question worth asking is not whether robots are green. It is whether we are honest enough about what we are measuring — and who decided what not to count.
1. Do AI robots actually reduce environmental waste? Yes, in the specific area of physical manufacturing waste — scrap, rework, and rejects all drop significantly when robots replace manual operations. The International Federation of Robotics identified precision-driven material savings as a core sustainability benefit in its 2025 trends report. But that reduction is only part of the environmental picture, and often the smaller part once AI training energy and hardware lifecycle costs are included.
2. How much energy do AI robots actually consume? The robots themselves are not the main issue — the AI models that make them smart are. Goldman Sachs Research projects that global data centre power demand will rise by 165% by 2030 compared to 2023 levels, driven primarily by AI workloads. In the US, data centre electricity consumption already represents about 4% of the national total and is projected to more than double by 2030. Training a single large AI model can consume as much energy as several average homes use in an entire year.
3. Is "sustainable robotics" just a marketing term? Currently, yes — for most companies. The dominant measure used in robotics ESG reporting is factory-floor scrap reduction, which ignores compute energy, raw material sourcing, and end-of-life hardware disposal. That is starting to change as European automotive and electronics supply chains now require full lifecycle ESG audits from suppliers. When losing a customer contract becomes the alternative, sustainable robotics stops being a marketing term and becomes a procurement specification.
4. Which part of the world leads in sustainable robotics practice? Europe leads on regulation and lifecycle audit requirements. Asia leads in raw deployment volume — accounting for 74% of new global industrial robot installations in 2024, according to IFR World Robotics 2025 — though much of that deployment runs on energy grids still dominated by fossil fuels. The US is caught between the two: a large existing deployment base with no federal lifecycle audit standard yet in place.
5. What should a company actually do to make its robotics investment genuinely sustainable? Three things that have nothing to do with the ESG slide deck. First, measure the full compute cost of any AI-driven optimisation — not just the material savings it produces. Second, require modular upgrade capability from vendors so hardware can be extended rather than scrapped every five to seven years. Third, ask who owns the operational data the robot generates — because you cannot audit what you cannot access, and most current vendor contracts answer that question in the vendor's favour.














