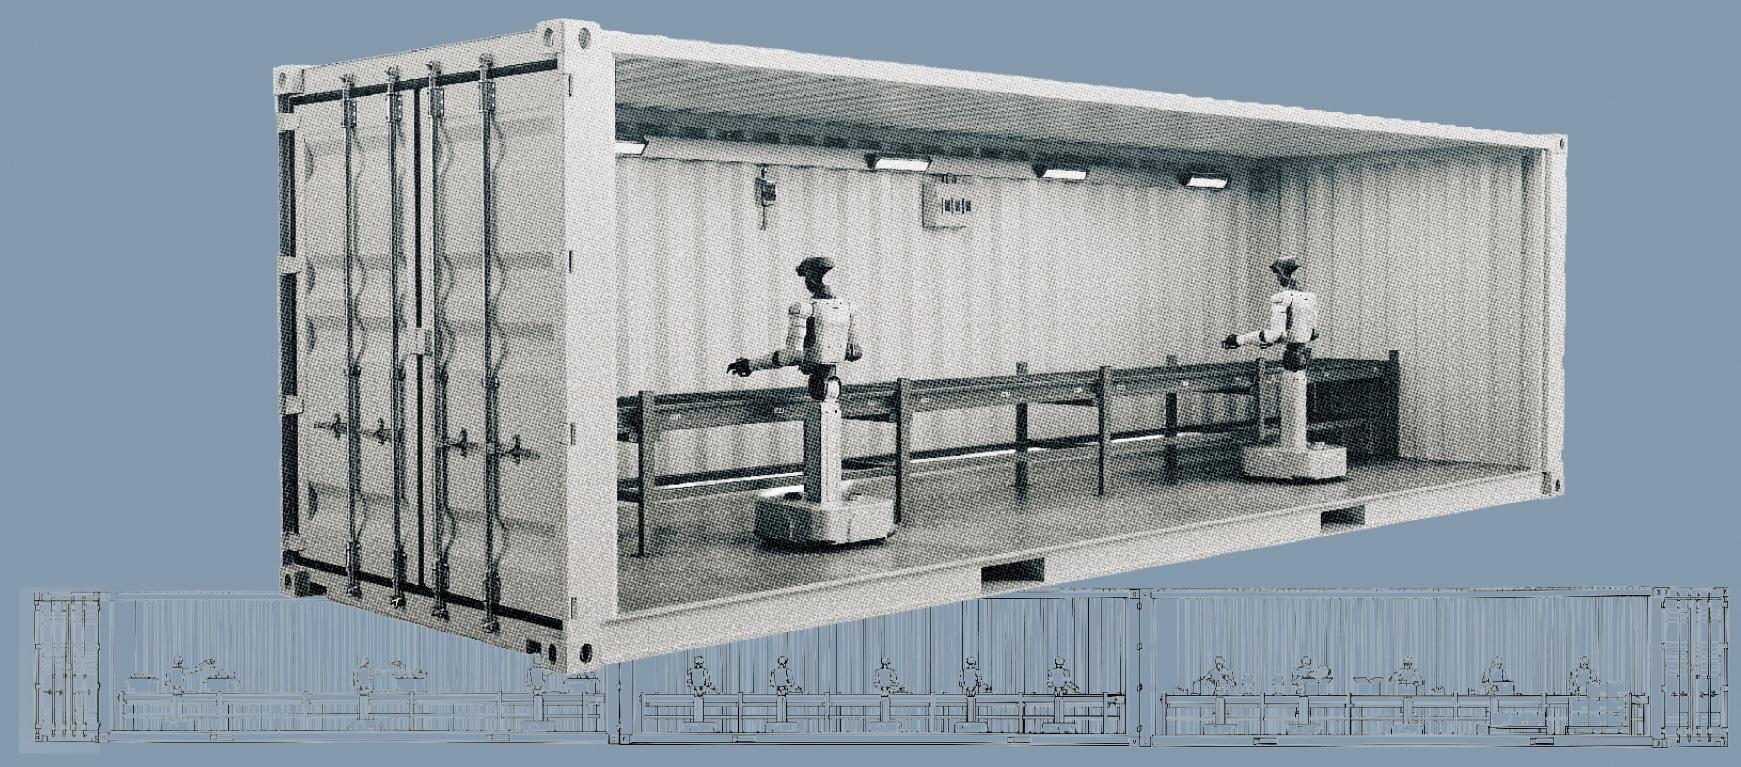
YOUIBOT Clears CSRC Filing Toward Hong Kong Listing Hearing
Mobile-manipulation robot maker YOUIBOT received a CSRC filing notice clearing the way for a Hong Kong listing hearing, backed by three years of accelerating revenue and margin growth in semiconductor and battery-plant automation.


China's robotics IPO pipeline has a new procedural marker to watch. On October 16, 2026, the China Securities Regulatory Commission published a filing notice for Hefei Youai Zhihe Robot Co., Ltd., the mobile-manipulation robot maker known commercially as YOUIBOT, covering the overseas listing of new shares and the "full circulation" conversion of its existing domestic unlisted shares into Hong Kong-tradable stock. The filing is a regulatory prerequisite, not a listing itself: it clears the way for a Hong Kong Stock Exchange hearing, the next formal gate before any shares actually trade. YOUIBOT, founded in 2017 by a team out of Xi'an Jiaotong University's robotics lab and now headquartered in Feidong County, Hefei, Anhui, builds wheeled mobile-manipulation robots that combine a robotic arm with an autonomous mobile base for use inside semiconductor fabs, battery plants and electronics factories.
The company's own framing is that this filing positions it to become the first listed company built specifically around mobile-manipulation robotics, a narrower category than the humanoid and industrial-arm names that have dominated recent China robotics listings. That claim is still unproven. A CSRC filing notice is not a trading debut, and the company has not disclosed a hearing date or a target pricing window. What is confirmed is the structure: YOUIBOT plans to issue up to 49,477,800 new overseas-listed ordinary shares, while 37 existing shareholders convert 243,804,260 domestic unlisted shares into overseas-listed stock. The company is applying under Chapter 18C of the Hong Kong exchange's listing rules, the track reserved for "specialist technology companies" that may not yet be profitable but meet revenue and research thresholds, with China International Capital Corporation acting as sole sponsor.
Why the Numbers Make the Listing Case Credible
Revenue growth is the strongest part of YOUIBOT's pitch to prospective shareholders. The company reported RMB108 million (approximately US$15.2 million) in 2023 revenue, RMB255 million (approximately US$35.9 million) in 2024, and RMB340 million (approximately US$47.9 million) in 2025, a three-year compound annual growth rate of roughly 77.5 percent. Gross margin rose over the same period from 26.1 percent to 36.5 percent, a trajectory that matters more to procurement-minded readers than the headline revenue figure, since it signals the company is gaining pricing power and component-cost efficiency as it scales rather than simply buying share with thinner margins. Cumulative research and development spending across the filing period exceeded RMB200 million (approximately US$28.2 million).
Customer retention backs up the margin story. YOUIBOT reports a repurchase rate above 70 percent across its 2025 customer base, broken out as 75 percent in semiconductors, 100 percent in lithium battery, and 78 percent in 3C and general manufacturing. A 100 percent repurchase rate in any single vertical is an unusually clean number for an industrial robotics vendor, and it suggests the battery-sector deployments in particular are structured as multi-phase rollouts rather than one-off pilot purchases. The company lists more than ten domestic and overseas wafer fabs among its customers, along with over 400 named accounts that include more than 50 Fortune 500 companies, and it holds more than 300 core intellectual property filings. It carries China's national "Little Giant" designation, a government classification reserved for small and mid-sized firms judged to hold specialized, hard-to-replicate technology in a narrow niche.
The Product Line Competing for Fab-Floor Budget
YOUIBOT's commercial lineup centers on three mobile-manipulation families: the OW series, built around 12-inch FOUP wafer-pod handling for semiconductor fabs; the ATS series; and the ARIS series, each pairing a collaborative or industrial arm with an autonomous mobile base rather than selling either component alone. Layered on top is FabriX, the company's scalable industrial foundation model intended to generalize across these hardware variants, and a separate "Tianyan" product family that includes a humanoid robot called Xifeng, the company's entry into the broader embodied-intelligence category that most of its mobile-manipulation peers are also chasing.
For a procurement team evaluating fab-floor automation vendors, the relevant comparison is not YOUIBOT against humanoid-robot makers chasing general-purpose labor replacement, but YOUIBOT against the narrower set of mobile-manipulation specialists competing for the same wafer-handling and battery-line budgets: a category where task-specific reliability, cleanroom compatibility and integration with existing fab automation software matter more than how human-like the robot looks. YOUIBOT's claim to rank first globally and first in China among industrial mobile-manipulation-robot makers by 2025 revenue, an estimate the company attributes to a third-party industry assessment, is the evidentiary basis for the "first mobile manipulation robot stock" framing now circulating in Chinese trade coverage. It is a revenue ranking within a specific hardware category, not an independently audited market-share figure, and buyers should treat it as directional rather than definitive until the listing prospectus itself discloses the methodology.
What the Chapter 18C Route Signals About Profitability
The choice of listing track is itself informative. Chapter 18C exists because Hong Kong's exchange wants to attract specialist technology companies, including robotics and advanced-manufacturing names, that would not clear a conventional profitability bar but meet alternative tests on revenue scale, research intensity or third-party validation of their technology. Companies that list under this chapter are implicitly disclosing that they are not yet consistently profitable on a net basis, even if gross margins are improving. For a buyer evaluating YOUIBOT as a long-term automation partner rather than a one-time equipment purchase, that matters: a newly listed, pre-profit vendor carries different vendor-risk considerations around long-term service continuity and spare-parts supply than an established industrial automation incumbent with decades of balance-sheet history.
That risk calculus cuts both ways, however. A successful Hong Kong listing would give YOUIBOT a public capital-markets channel to fund the production capacity and overseas service infrastructure that semiconductor and battery customers increasingly expect from a hardware vendor before committing to multi-year deployments, rather than relying solely on private venture rounds. The CSRC filing notice, read narrowly, is simply confirmation that Beijing's securities regulator has processed the paperwork needed for that overseas capital-raising path to proceed. Read against the revenue and margin trajectory disclosed so far, it is also a signal that one of China's more narrowly focused robotics categories, wafer and battery mobile manipulation, has produced at least one vendor with a credible public-markets growth story independent of the humanoid-robot hype cycle dominating most 2026 China robotics coverage.
A Widening Field of China Robotics Names on the Hong Kong Exchange
YOUIBOT would not be entering Hong Kong's exchange as an isolated test case. A growing number of China-based robotics manufacturers have used the same Chapter 18C route or conventional listing tracks over the past two years to raise capital without first reaching net profitability, spanning industrial-arm makers, collaborative-robot vendors and now, if YOUIBOT clears its hearing, a mobile-manipulation specialist. That pattern reflects a deliberate choice by Hong Kong's exchange operator to compete with Nasdaq and Shanghai's STAR Market for Chinese advanced-manufacturing listings by lowering the profitability bar in exchange for stricter technology-validation and disclosure requirements. For institutional investors building China robotics exposure, the practical effect is a widening menu of single-category plays, letting a fund choose exposure to wafer-handling automation specifically rather than buying a diversified industrial-robotics basket that blends collaborative arms, AGVs and humanoid prototypes with very different commercial maturity.
That specialization is also what differentiates YOUIBOT's pitch from the humanoid-robot listings generating most of this year's China robotics headlines. Humanoid makers are, almost without exception, pre-revenue or early-revenue businesses selling a capability still being proven in real deployments. YOUIBOT is instead asking the market to value a business with three consecutive years of audited-adjacent revenue growth, customer-repurchase data by vertical, and named Fortune 500 accounts, a profile closer to a traditional industrial-automation supplier than to a speculative embodied-intelligence story. Whether public investors reward that profile with a valuation premium over flashier humanoid listings, or instead discount it for operating in a narrower niche with a smaller total addressable market, will become clearer once YOUIBOT's hearing documents disclose a proposed valuation range.
The Procedural Steps Still Standing Between Filing and Trading
Three steps remain before YOUIBOT shares change hands on the Hong Kong exchange: a formal listing hearing, pricing and allocation of the offering, and the trading debut itself. The CSRC filing notice addresses none of these directly; it only confirms that the cross-border regulatory paperwork on the mainland China side is in order. Companies have, in prior cases, cleared CSRC filing and still faced delays or withdrawals at the hearing stage over disclosure questions or market conditions, so the filing notice is better read as a milestone in a multi-month process than as a confirmed listing date. YOUIBOT first submitted its Hong Kong listing prospectus in September 2025, meaning this filing notice arrives roughly thirteen months into the process, a timeline consistent with other recent China-to-Hong Kong technology listings rather than an unusually fast or slow track.
For buyers tracking which mobile-manipulation vendors are building the balance-sheet strength to support multi-year fab and battery-plant contracts, YOUIBOT's CSRC filing is the clearest public confirmation yet that its revenue and margin numbers have cleared the first regulatory bar toward an independent, audited public listing. Whether that translates into the "first mobile manipulation robot stock" distinction the company is claiming now depends on execution through the hearing and pricing stages still ahead, not on anything the filing notice itself guarantees.
This account synthesizes trade reporting on YOUIBOT's October 16, 2026 CSRC filing notice, cross-referenced against public reporting on the company's September 2025 Hong Kong listing prospectus submission, as of the stated publication date.
This article is provided for general information purposes only and does not constitute investment, procurement, legal, or engineering advice. Figures reflect the sources listed above as of the stated information cut-off and may change without notice.