
SASAC unveils central enterprise robotics consortium at WRC 2026 for embodied AI
China’s state assets regulator will launch a Central Enterprise Robotics Innovation Consortium at WRC 2026 and debut a dedicated SOE pavilion. Forty nine central SOEs will present twelve scenarios across heavy industries, signaling direct state backed deployment of humanoid robots as a national testing ground.
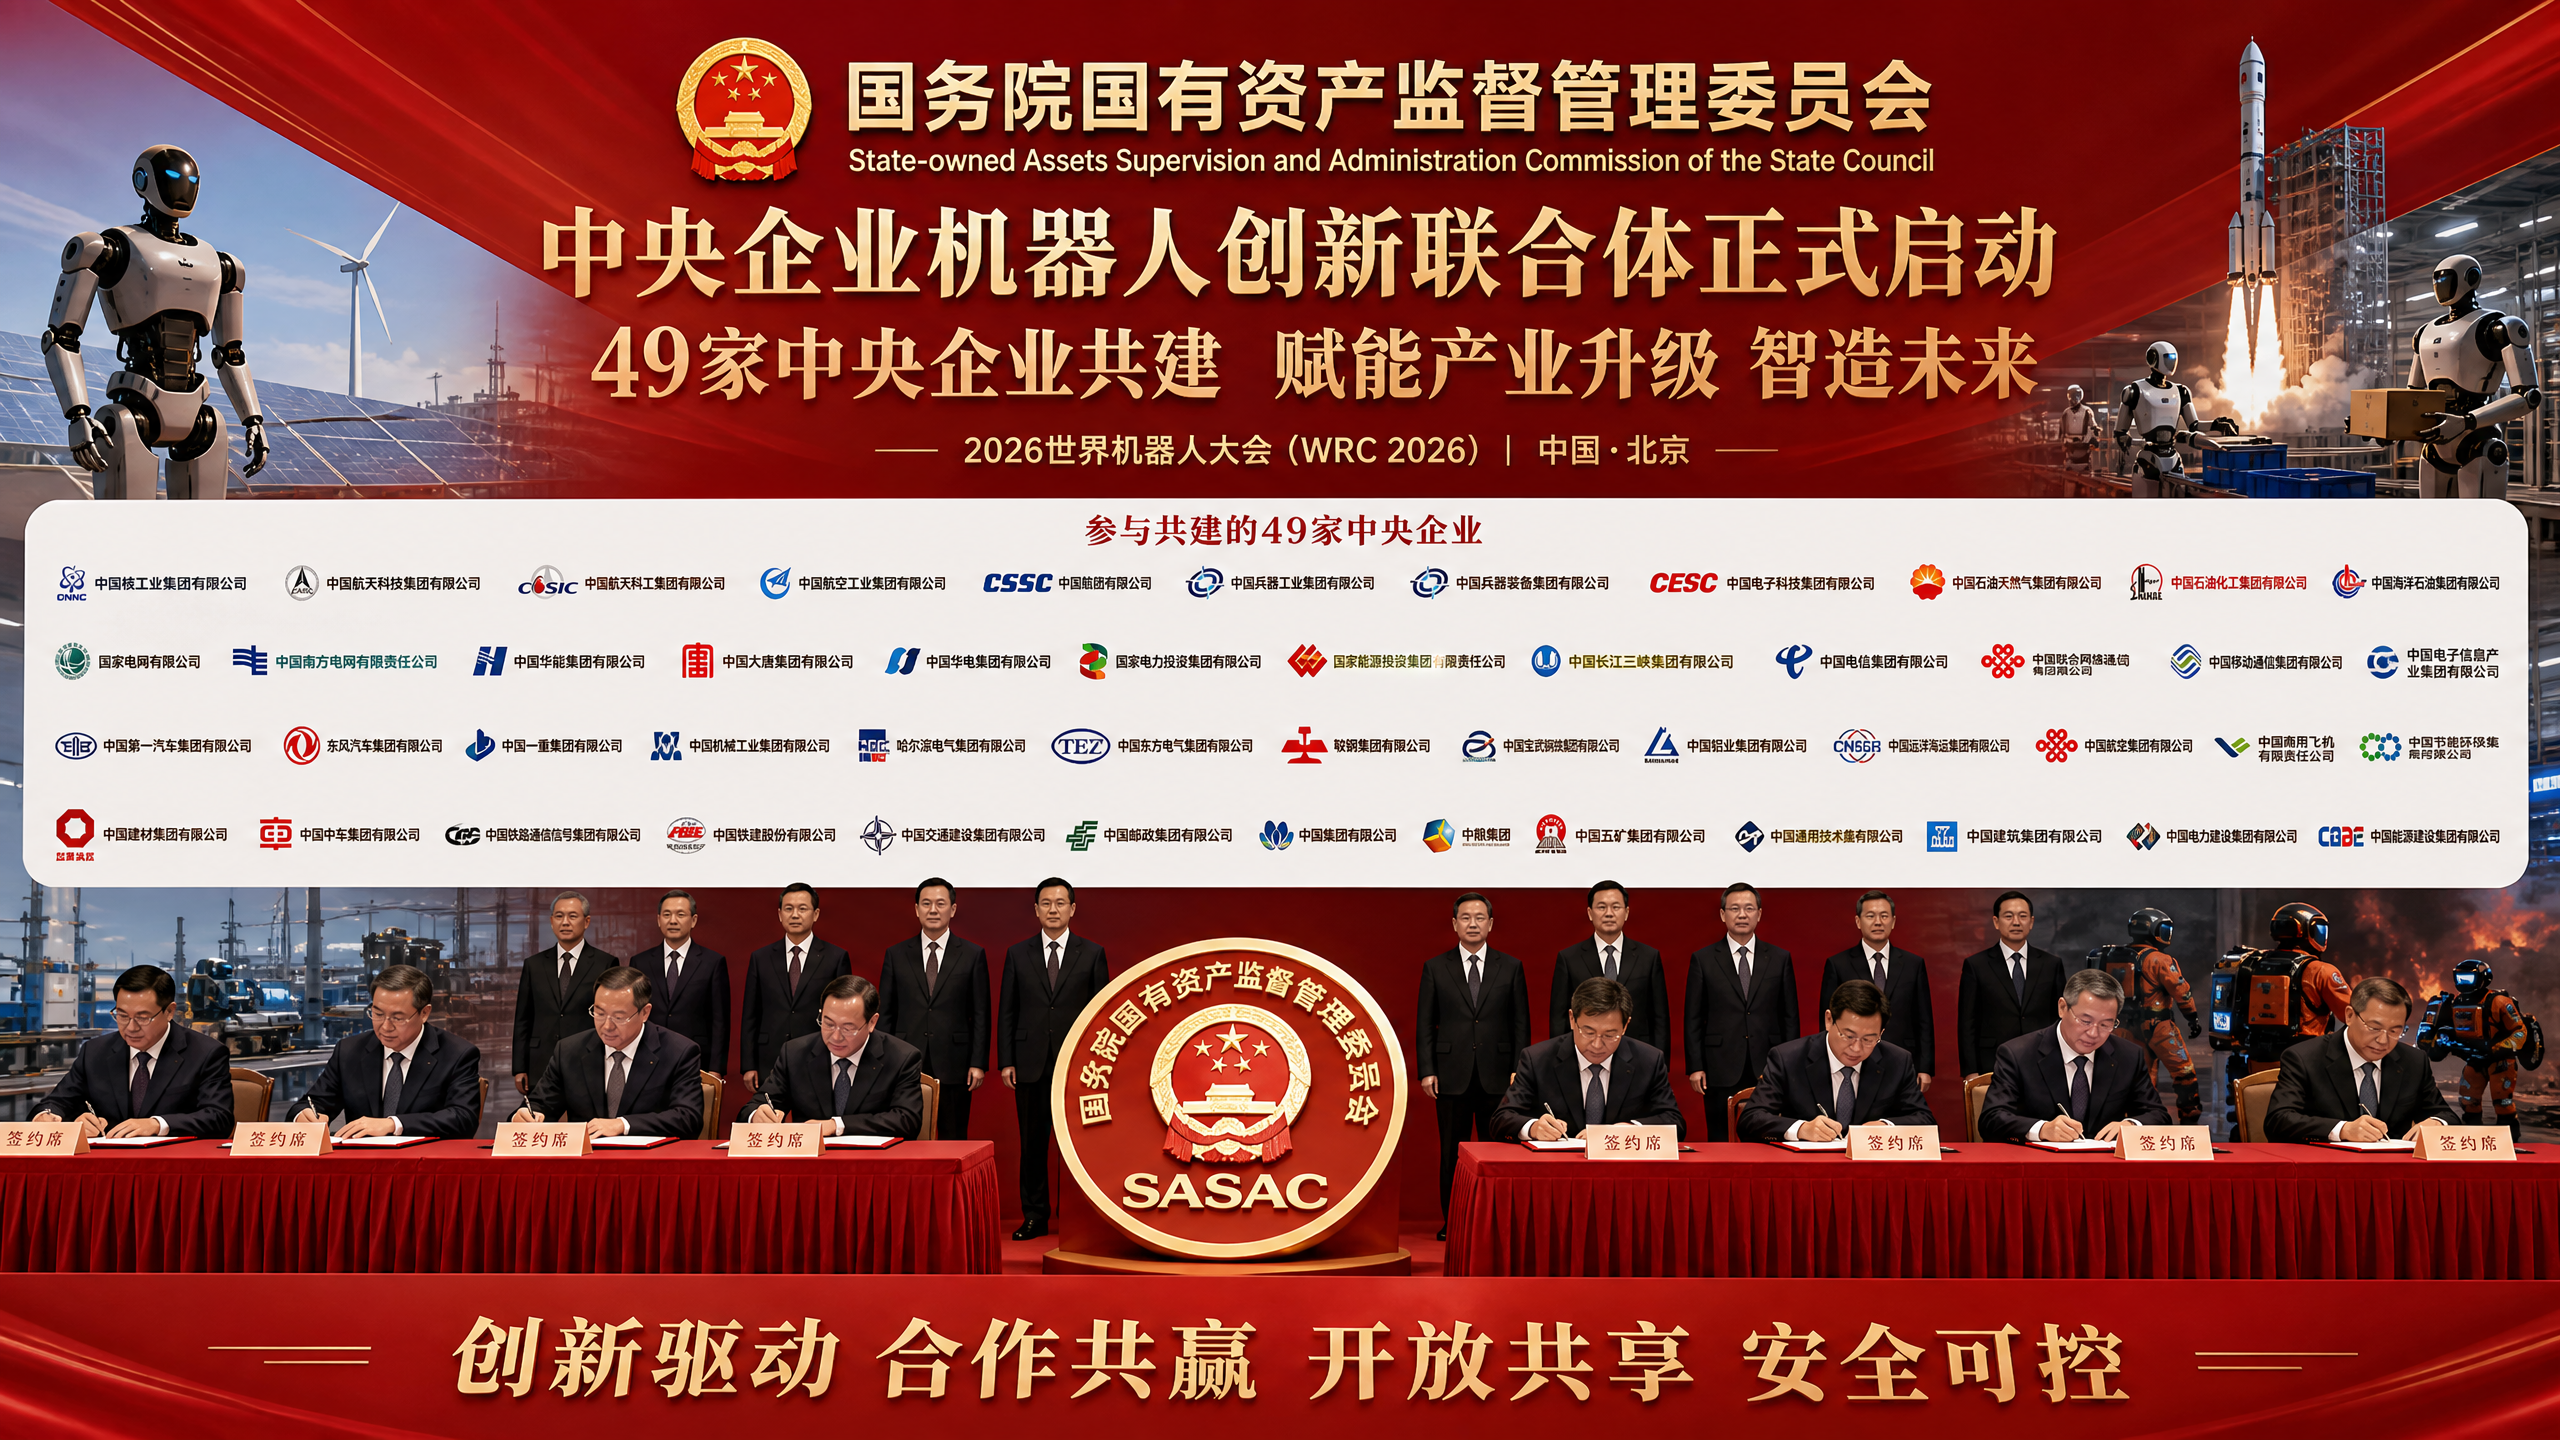
Beijing will host a new state led robotics initiative at WRC 2026. State‑owned Assets Supervision and Administration Commission of the State Council ("SASAC") will launch the Central Enterprise Robotics Innovation Consortium alongside a dedicated state-owned enterprise pavilion.
Forty nine central SOEs will present twelve application scenarios spanning energy, aerospace, manufacturing, logistics, and emergency response. The initiative shifts China from subsidies toward direct SOE deployment and testing of humanoid robots.
Role of SASAC
SASAC, the Beijing based oversight body for China’s central state-owned enterprises, is turning embodied AI from a policy priority into a procurement machine. The new consortium, revealed for WRC 2026, formalizes state buyers as anchor customers and deployment partners for humanoid and mobile manipulation systems. In a market where most Western pilots remain limited to proof of concept trials, China is preparing to use its SOE behemoths as a guaranteed funnel for demand, data, and iteration. The shift reconfigures the competitive field for robotics and the upstream components that feed it, from actuators and harmonic reducers to edge compute and lithium cells.
State assets are moving from policy nudges to purchase orders China has spent a decade nurturing robotics through subsidies, tax incentives, and municipal demo zones. That created volume in cobots, AGVs, and specialized arms for electronics and automotive. Humanoids remained a frontier category with eye catching demos and scattered pilots. By placing SOEs at the center of procurement, Beijing is moving past grants and glossy showcases into a structured purchase order regime backed by long lived infrastructure owners.
Upcoming WRC to Showcase Unified Use Case Scenarios
This is not a generic expo maneuver. WRC will house a first ever pavilion that clusters 49 central SOEs around twelve unified scenarios. Energy operators can test robots for substation inspections and valve operations. Aerospace and rail contractors can trial dexterous maintenance in depots. Logistics groups can pressure test sorting, palletizing, and last hundred meter solutions. Emergency responders can simulate hazardous area reconnaissance. The signal is unambiguous. The state wants humanoids and mobile manipulators inside core national assets, not only inside labs.
SASAC uses SOE scale to manufacture demand for humanoid robots SASAC controls a fleet of national champions that own grids, pipelines, railways, shipyards, air fleets, mines, and telecom networks. These enterprises hold assets measured in the trillions of RMB and operate thousands of sites across provinces. They can tender multi year frameworks, standardize specifications, and build training campuses. For humanoid builders, this is the difference between fighting for pilot scraps and tapping into a predictable cadence of deployments that compound into a learning curve.
Think of it like a coach reserving entire stadiums for practice rather than a few borrowed gym hours. Consistent field time and repetitive drills are what bring error rates down and performance up. In robotics that means putting machines into varied, messy, and repeatable tasks with human supervisors, and capturing telemetry until failure patterns become solvable.
The consortium structure points to a procurement first playbook Labels matter in Beijing. By naming a Central Enterprise Robotics Innovation Consortium, SASAC is signaling structure. Expect working groups that align use cases, KPIs, and safety protocols. Expect shared pilot facilities where vendor neutral testbeds can be staged with the same fixtures and digital twins used across SOEs. Expect procurement templates that move from exploratory trials to staged rollouts, with annual quotas tied to performance gates.
This reverses the patchwork that often slows diffusion. In many countries, pilots remain stuck in innovation outposts without operational buy in. A consortium with SASAC at the helm can move from lab to line by assigning accountable line owners and measurable cost or safety targets. Vendors that clear the bar earn fleet purchase paths. Vendors that do not are recycled quickly, avoiding pilot purgatory.
National Sandbox for Embodied AI Robotics
The SOE pavilion functions as a national sandbox for embodied AI Robotics thrives on data, and embodied AI needs depth more than breadth. It is not enough to have a handful of clips showing a robot folding laundry in a lab. Industrial deployment requires millions of interaction frames for a narrow set of tasks in a fixed environment. A substation has valves, ladders, cable trays, and panels. Those are the same in thousands of substations. A humanoid that masters those elements can scale across a fleet.
The pavilion model lets SOEs curate tasks that are numerous enough to matter yet constrained enough to learn quickly. Visual models can be trained on consistent scenes. Force control can be tuned for identical clamps and latches. Teleoperation routines can be standardized and pushed to frontline crews. The result is a national sandbox that feeds embodied AI with coherent, high fidelity data. It is the opposite of random YouTube pretraining. It is repetitive practice on jobs that pay the bills.
Supply Chain to fulfill SOE Demand
Supply chains for actuators sensors and compute gain an accelerant Guaranteed demand moves upstream prices and yields. Servo motors, harmonic reducers, torque sensors, high efficiency gearboxes, and silicone encapsulated grippers are all cost sensitive components that suffer from long lead times and variable quality. A coordinated SOE demand signal can unlock larger tooling investments at local suppliers, pull forward capex in machining and heat treatment, and drive batch testing to tighten tolerances.
Domestic players in reducers and motors have been chipping away at Japanese incumbents. Consortia orders will help Chinese makers win qualification runs inside state industrial assets. That shortens the path from pilot grade parts to safety certified production parts. Vision sensors, depth cameras, and millimeter wave radar units will also benefit from pooled specifications. On compute, export controls on high end GPUs have already pushed companies toward domestic accelerators, such as NPUs and Ascend class devices. A shared middleware stack that runs on indigenous chips would harden supply lines against sanctions while forcing the software layer to be portable.
Battery chemistry and thermal management will get a tailwind as well. Humanoids need dense, safe packs that can be swapped or recharged without excessive downtime. SOE logistics depots and grid companies can standardize charging bays and battery formats, similar to the early days of forklift electrification. That alone can shave minutes off turnaround and translate into measurable availability gains.
Solution to Support Domestic Players
Competitive pressure builds on private startups at home and abroad The consortium is not a closed club for state factories. Private challengers like Unitree, Fourier, UBTech, and emerging labs will need to either plug into SOE frameworks or pivot to export and commercial service niches. The attractive option is to win a place on the approved vendor lists that SOEs will maintain. That offers volume and cash flow in exchange for compliance with safety and service level rules.
Internationally, the effect is sharper. Western humanoid makers such as Agility, Figure, and Apptronik have secured pilots with big names including Amazon, BMW, and NASA. Those are significant, but they remain limited in site count and run time. A national buyer cohort with dozens of state sites changes the slope of the learning curve. Chinese suppliers can iterate weekly across thousands of hours of exposure in harsh industrial settings. That produces better motion planning, more robust end effectors, and faster failure diagnosis. As with photovoltaics and EV drivetrains, cumulative manufacturing and field experience can outweigh individual breakthroughs.
Deployment and Scability
Energy telecom and rail provide early low hanging deployment fields The scenarios most likely to scale first are those with high repetition, moderate dexterity, and large installed bases. Power transmission corridors and substations fit this bill. Routine tasks such as thermographic scanning, corrosion checks, indicator readings, breaker toggles, and small tool operations do not require Olympic level balance or fingertip articulation. Rail depots and rolling stock yards also present repeatable cleaning, inspection, and minor maintenance tasks that humanoids or mobile manipulators can adopt.
Telecom operators can deploy robots for base station inspections, battery swaps in remote cabinets, and inventory moves within centralized warehouses. Petrochemical parks, while more complex, can start with non explosive zones and emergency response drills. Ports and bonded warehouses can experiment with mixed pallet flows and strapping. None of this requires fully general purpose humanoids. A pragmatic approach that starts with narrow tasks and expands as competence grows is consistent with how automation has usually succeeded.
Safety and Governance
Safety governance and labor politics present real execution risk The shift from lab to line brings real safety stakes. Humanoid robots moving near high voltage equipment, heavy rolling stock, or pressurized pipelines demand strict interlocks, reliable fail safes, and clear human in the loop rules. Incidents would spark scrutiny from regulators and could slow the rollout. The advantage of the consortium model is that safety baselines can be unified. The risk is that a single failure can echo across many sites.
Labor dynamics are delicate as well. SOEs have social obligations and cannot be seen as cavalier about jobs. The near term framing will likely emphasize three themes. First, safety by removing humans from hazardous tasks. Second, filling shortages where remote or harsh sites struggle to attract workers. Third, productivity gains that support wage growth rather than headcount cuts. This messaging is common in industrial automation and aligns with political priorities. Execution must match the rhetoric. If robots arrive while headcounts fall, backlash will follow.
Export Controls and Challenges
Export controls widen the fork in compute paths US restrictions on advanced GPUs and the broader squeeze on cutting edge lithography have already forced Chinese AI developers to adjust. Embodied AI compounds the challenge because training large visuomotor models and running real time inference on edge devices both push hardware limits. The consortium will likely catalyze two parallel tracks. Training on domestic accelerators with optimized frameworks and quantization techniques, and edge inference on dedicated NPUs tightly coupled with sensors.
That path can win in controlled tasks but may lag in generalization compared with models trained on US leading hardware. However, the SOE focus on narrow, repeatable scenarios reduces the penalty of lacking the absolute peak of compute. The priority becomes reliability, latency, and predictable performance in fixed environments rather than state of the art benchmarks for open ended skill sets.
Robotics Costs
Cost curves hinge on field failure data and repair logistics Industry estimates peg humanoid platforms today between US$70,000 and US$200,000 per unit, depending on specs, volume, and support. Those numbers only make sense for buyers if the robots do useful work for long stretches without expensive downtime. The bulk of the cost drop will not just come from cheaper parts. It will come from better mean time between failure, faster swap procedures, and predictive maintenance that catches small issues before they cascade.
Field telemetry across dozens of SOE sites is the raw material. Teams can map failure modes by environment. Dust ingress in desert substations is one profile. Condensation in coastal depots is another. Vibration induced connector creep on rail yards is a third. Standardized repair kits, modular limbs, and easy access panels can reduce service time. SOE wide service depots and training centers can turn scarce robotics technicians into a mobile force that moves between sites. These are mundane details that separate successful deployments from flashy prototypes.
Market Impacts and Competition
Western manufacturers face a delayed but steeper competition wave The short term effect of the consortium will be most visible inside China. Domestic deployments will move first because procurement and support are easier. Over a two to three year window, as Chinese vendors stabilize their platforms and certify safety, expect an export push into Belt and Road partner countries and price sensitive markets. That is where the scale advantages of a state anchored demand curve will bite.
Western manufacturers with higher unit economics will emphasize premium features and deep integration in advanced factories. Some will partner with Chinese suppliers for components or subassemblies to keep costs manageable. Others will double down on sophisticated dexterity and autonomy aimed at aerospace, pharma, or electronics plants that value precision over price. The risk for Western firms is not only cost. It is the sheer pace of iteration that comes from thousands of hours of diverse field exposure, which breeds robustness that labs cannot fake.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice.













