Kawasaki lines up JPY 193.4 billion for robotics, physical AI
Kawasaki Heavy Industries expects about JPY 193.4 billion in net proceeds from a new share offering and a bond offering. The allocation includes robotics manufacturing capacity, a Nishi-Kobe Works investment to raise supply for semiconductor robotics, and about JPY 30.5 billion for physical artificial intelligence research and development, strategic alliances, and debt repayment or bond redemption.
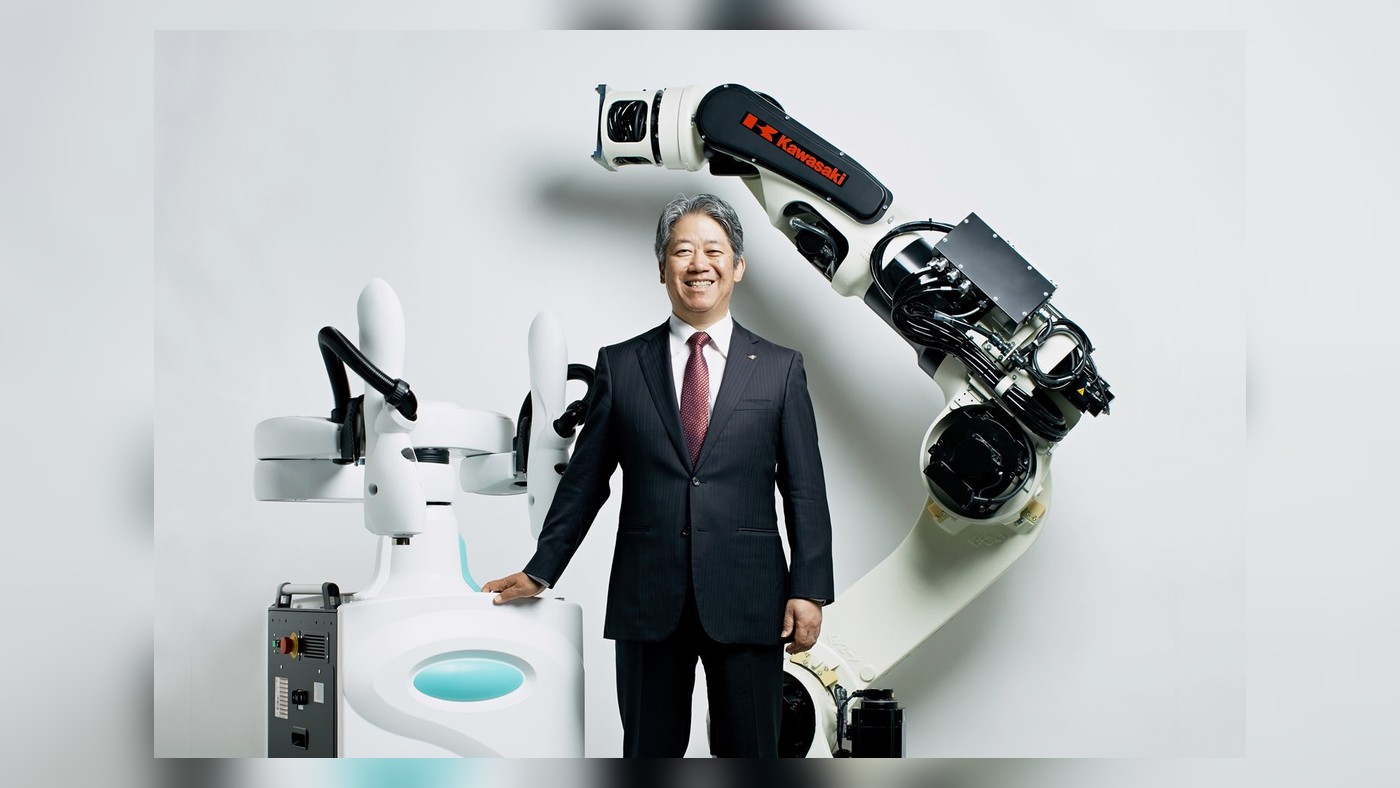
Kawasaki Heavy Industries expects combined net proceeds of approximately JPY 193.4 billion, about US$1.32 billion using an indicative exchange rate of JPY 147 to US$1, from a new share offering and a bond offering announced in its 14 July 2026 notice. Kawasaki Heavy Industries, a Tokyo headquartered industrial conglomerate and major industrial robotics manufacturer, is allocating the financing across several programs, including manufacturing facility investment involving robotics and physical artificial intelligence, robotics business investment at Nishi-Kobe Works to increase production capacity for robots used in semiconductor manufacturing equipment, and approximately JPY 30.5 billion, about US$207 million, for physical artificial intelligence research and development, strategic alliances, and debt repayment or bond redemption.
The headline financing figure is large, but procurement teams should read it with discipline. This is not a pure robotics raise, not a product launch, and not a guarantee of shorter lead times. It is a capital allocation move by a diversified industrial manufacturer that is trying to fund capacity, research, alliances, and balance sheet management across a multi year schedule. The robotics and physical artificial intelligence allocations should also be kept separate from Kawasaki’s larger liquefied hydrogen investment program, because the commercial drivers, payback profile, and buyer relevance are different.
What Kawasaki’s financing means for automation buyers right now
Kawasaki’s financing matters because it links a specific semiconductor robotics capacity expansion at Nishi-Kobe Works with a broader program covering manufacturing, physical artificial intelligence, alliances, and balance sheet uses. Buyers should treat it as evidence of funded intent and future supply capacity, not as proof that extra robots or new features are available today.
A buyer who reads the package as a blanket signal for faster delivery will be disappointed. A buyer who treats it as a structured commitment to capacity, longer horizon research, and corporate financing will be closer to the mark. The financing notice provides a timetable for how capital may flow into production and technology activity, not an instant change in available inventory.
Kawasaki’s message is specific where it matters most for semiconductor equipment supply. The Nishi-Kobe Works investment is aimed at increasing production capacity for robots used in semiconductor manufacturing equipment. That is the most concrete operations oriented element for procurement managers who have been managing tight delivery windows or qualification delays in that category.
Inside the announced financing: amounts, timing, and uses
The financing package combines equity proceeds and bond proceeds. Kawasaki outlines expected net proceeds of approximately JPY 92.4 billion from the share offering to be used through March 2029, and approximately JPY 101 billion from the bond offering to be used through March 2031. Combined expected net proceeds are approximately JPY 193.4 billion, about US$1.32 billion at JPY 147 to US$1 for context.
These timeframes match how heavy industrial projects are executed. Facility investment, robotics capacity expansion, physical artificial intelligence research and development, alliances, and refinancing do not move at the same speed. A factory modification that affects robot throughput and quality control has planning, installation, hiring, and validation stages. Research programs and alliance work often advance in parallel, with deliverables that then need to be integrated into products.
Yes, robotics is directly included in the use of proceeds. The allocation covers robotics related manufacturing facility investment and robotics business investment at Nishi-Kobe Works. The Nishi-Kobe investment is aimed at increasing production capacity for robots used in semiconductor manufacturing equipment.
Yes, physical artificial intelligence is also directly included, but it should be read carefully. Approximately JPY 30.5 billion, about US$207 million, is allocated across physical artificial intelligence research and development, strategic alliances, and debt repayment or bond redemption. That means not all of that amount should be treated as pure new research and development spend.
This read differs from a narrow technology marketing teaser. It is a blended capital plan across facilities, technology, alliances, and corporate finance. That mix is common for a company with multiple industrial businesses and long cycle engineering demands.
Why Nishi-Kobe semiconductor robotics capacity is the key operational signal
Kawasaki’s robotics business investment at Nishi-Kobe Works is aimed at increasing production capacity for robots used in semiconductor manufacturing equipment. For buyers, that sentence carries more supply chain meaning than the aggregate JPY 193.4 billion total. It targets a clear production bottleneck and a defined customer segment where the switching costs of changing robot platforms are high.
Semiconductor manufacturing customers do not buy robots like a general factory buyer purchasing palletizing or arc welding automation. The robot is integrated into a larger toolchain, often through semiconductor equipment firms, system integrators, and factory automation platforms. Once a robot is qualified in a tool architecture, replacing it can require renewed qualification, software rework, and updated service routines. That raises the bar for both investment and execution.
Dedicated Nishi-Kobe capacity can support three commercial objectives. First, it can give Kawasaki more room to serve semiconductor equipment demand without cannibalizing other robot lines. Second, it can improve schedule credibility with customers who plan deliveries several quarters ahead. Third, it can support specialization in cleanroom requirements, process integration, and reliability built for high value production tools.
The caveat is timing. An investment designed to increase production capacity is not the same as immediate additional supply. Factory projects must pass through planning, equipment procurement, installation, staffing, process validation, and yield improvement. In this category, quality is inseparable from output. Robots that support wafer handling and cleanroom workflows are judged by uptime, contamination control, precision, repeatability, service response, and qualification history. Those conditions are stricter than general purpose automation.
Why semiconductor robot capacity resembles a controlled production line
A normal industrial robot factory is like a kitchen that can prepare many reliable meals. A semiconductor robot line is more like a kitchen preparing food for a hospital surgery room. The meal still needs to be made efficiently, but the rules for cleanliness, consistency, timing, and traceability are much stricter.
Robots used around semiconductor manufacturing equipment must perform repeated movements with high precision and low tolerance for error. They may operate where contamination, vibration, positioning mistakes, or downtime disrupt expensive production. The robot is not judged only by whether it moves. It is judged by whether it moves the same way, under strict conditions, over long operating periods, while fitting into equipment and factory systems that have already been validated.
That is why a general increase in robot factory output may not solve a semiconductor robotics constraint. Dedicated capacity can mean production cells, test setups, trained technicians, component sourcing, quality inspection routines, and documentation systems aimed at a specific robot category. It also gives the supplier more control over repeatability. For semiconductor equipment builders and fabrication plants, repeatability is often as valuable as raw volume.
For procurement managers, the simple version is this. Semiconductor robots are not just more robots. They are robots tied to high cost manufacturing environments where qualification and reliability carry heavy financial consequences. Dedicated expansion is the practical way to increase supply without weakening control over quality.
Why the financing cannot be counted as pure AI spending
A common error is to treat any financing line that mentions physical artificial intelligence as evidence of a dedicated robotics technology fund. Another error is to dismiss the same line because debt repayment or bond redemption is included. Both views miss the structure of corporate capital planning.
Physical artificial intelligence inside a large industrial company is funded through the same machinery that funds factories, alliances, and refinancing. That does not make the physical artificial intelligence intent meaningless. It does mean the allocation is not as clean as a startup round where capital is raised for one narrow roadmap.
For buyers, this distinction is healthy. General corporate debt can finance the overall capital structure. Physical artificial intelligence funding can support research, partnerships, and systems that may later affect robot performance. Debt repayment can reduce future financial pressure. These uses can coexist, but they should not be counted twice.
A procurement team should avoid saying, “Kawasaki raised JPY 193.4 billion for physical artificial intelligence.” That is inaccurate. A better statement is that Kawasaki expects approximately JPY 193.4 billion in combined net proceeds from share and bond offerings, with proceeds allocated across manufacturing facility investment, robotics capacity at Nishi-Kobe Works, physical artificial intelligence research and development and alliances, and debt repayment or bond redemption, among other stated uses.
That wording keeps expectations grounded. It prevents overestimating the maturity of future features while also recognizing the value of balance sheet strength. A supplier that funds capacity expansion while managing debt obligations may be better positioned to support long term contracts than a supplier that overcommits to new technology without funding its manufacturing base.
What procurement teams should verify before relying on the expansion
Procurement teams should turn Kawasaki’s financing into a structured supplier review rather than a headline reaction. A practical scorecard covers six areas that reflect how financing turns into supply assurance.
Capacity specificity should be confirmed by robot model, subassembly, and production line. The Nishi-Kobe investment may not apply uniformly across every robot that touches semiconductor environments. A broad capacity increase does not solve a narrow bottleneck unless it applies to the constrained platform.
Timing and milestones should be requested from facility investment through qualified output. With use periods extending through March 2029 for share proceeds and through March 2031 for bond proceeds, buyers should expect phased availability and should tie commitments to documented milestones.
Quality controls must scale with output. Semiconductor related robots add cleanroom, precision, and reliability demands that can be degraded if production expands faster than quality systems. Buyers should look for evidence that calibration, contamination control, and documentation standards will be preserved as capacity rises.
Component supply coverage is necessary. Motors, drives, controllers, sensors, precision parts, and electronics are not created by factory floor space alone. If upstream components face constraints, a facility investment will not address all bottlenecks. Supplier plans for critical part sourcing should be part of contract diligence.
Service readiness deserves attention. More installed robots require field service capacity, spare parts planning, technical documentation, and training infrastructure. Contracts should specify service response, parts stocking, and escalation paths that match the expected installed base growth.
Physical artificial intelligence maturity needs to be separated into features available now, features in pilot, and research programs. Buyers should seek field evidence and safety cases, and should confirm how data rights, software update validation, and support responsibilities are handled if alliance partners are involved.
For semiconductor equipment makers, these checks should be embedded in sourcing conversations. For factory automation buyers outside semiconductors, they still matter. If Kawasaki allocates more dedicated resources to semiconductor robotics, buyers should monitor the availability and support levels for other robot families and ask how production planning aligns across segments.
The capital allocation signal for the next purchasing cycle
Kawasaki’s JPY 193.4 billion financing package places robotics and physical artificial intelligence inside a broader industrial funding plan. The share offering provides approximately JPY 92.4 billion in expected net proceeds through March 2029. The bond offering provides approximately JPY 101 billion in expected net proceeds through March 2031. Within the use of proceeds, robotics capacity at Nishi-Kobe Works and physical artificial intelligence related activity are meaningful for automation buyers, but they are not the only uses of capital.
The most actionable point is that Kawasaki is making a targeted capacity move in robots for semiconductor manufacturing equipment. That is a segment where supply credibility, qualification discipline, and long term service support matter as much as unit volume. The physical artificial intelligence allocation adds a future capability signal, but buyers should separate research and alliances from deployed product performance.
For procurement managers, the right response is not excitement or skepticism by default. It is supplier engagement with sharper questions. Ask which robot platforms are affected, when qualified output increases, how service capacity scales, which artificial intelligence features are commercially available, and how Kawasaki will protect support commitments across long life automation assets.
Kawasaki’s financing should be treated as a serious scale up indicator for selected robotics capacity and a measured signal of physical artificial intelligence investment, with procurement value determined by execution, qualification, and contractual clarity.
This analysis synthesizes official company statements and publicly available operating disclosures.
Disclaimer: This analysis is for informational purposes only and does not constitute investment, financial, or procurement advice. The views expressed are based on public information and industry trends as of the publication date. No vendor is endorsed, and no technology performance is guaranteed.